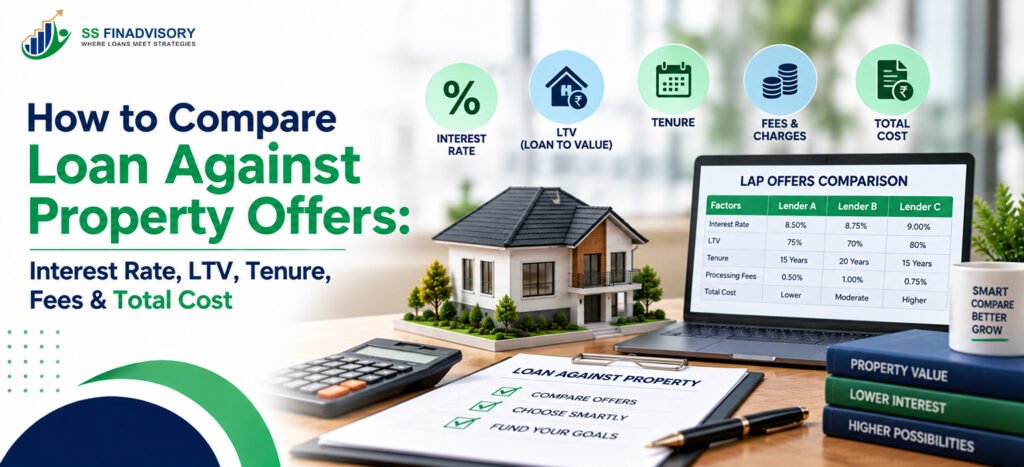
You like the loan amount one bank is offering, but the EMI from another looks lighter. When you sit down to compare loan against property offers, every lender in India seems to highlight a different number and hide a different condition.
If you simply pick the lowest EMI, you can end up paying more interest, blocking your property for longer, or getting stuck with harsh charges when you refinance or prepay. A little structured comparison upfront can save you several lakhs over the life of a LAP.
Start With The Real LAP Interest Rate Comparison
Lenders advertise a headline rate, but two offers at the same percentage can still cost you very differently. The first step in any LAP interest rate comparison is to strip the offer down to its basic pricing: benchmark rate, spread, and type of interest (fixed, floating, or a mix).
In India, most loan against property products are linked to an external benchmark or an internal reference rate. Ask each lender: what is the benchmark, what is the current value, what is the spread, and how often can the rate be reset. A “lower” rate that can reset frequently without clear rules can be riskier than a slightly higher but well-documented one.
Don’t just rely on the salesperson’s word. Check the sanction letter draft and any rate reset conditions carefully. If you’re not sure how to read those details, a specialised LAP advisory firm can help you interpret the fine print before you commit.
Understand The LAP LTV Ratio And How It Limits You
The next big lever in a loan against property comparison is the LTV ratio – the percentage of your property’s market value that the lender is ready to fund. One bank may cap you at a lower LTV, forcing you to borrow less and arrange more money from elsewhere, while another may stretch LTV but charge more interest.
This is where many borrowers in India trip up. A higher LTV feels attractive because it increases the sanction amount, but it also pushes your EMI higher and leaves less safety margin if property prices soften or your income drops. If your purpose is business expansion or working capital smoothing, a more conservative LTV with better pricing can be healthier for cash flow.
Also compare how each lender is valuing your property. Some rely only on their empanelled valuer, others may consider recent registered agreements in your area more aggressively. A focused LAP advisory, such as the LAP Smart Leverage Advisory, can help you structure the right LTV for your goal instead of just chasing the maximum possible amount.
Match LAP Tenure To Your Cash Flow, Not Just EMI Comfort
Tenure looks like a simple slider – increase tenure, EMI drops. Many borrowers treat LAP tenure as just an EMI adjustment tool. That’s the reason they end up paying interest for far longer than necessary.
When you compare tenures, look at two views side by side: EMI affordability over the next 12–24 months, and total interest outgo over the full term. A very long LAP tenure may “fit” your EMI budget today but can lock your property for a decade or more and reduce your flexibility to raise future loans against the same asset.
If your LAP is for business purposes, try mapping the tenure to your expected business cash flows. For example, if you expect profits to stabilise in three to five years, you might choose a slightly tighter tenure now and plan for partial prepayments down the line, rather than stretching to the maximum allowed term.
How To Compare Loan Against Property Tenure Options
A practical way to compare tenure options is to create three scenarios: conservative, base, and aggressive. The conservative option keeps EMI very comfortable; the aggressive one is close to your maximum safe EMI; the base is somewhere in between. Then compare the total interest in each case, not just the monthly outgo.
Online LAP EMI calculators can help you do this side-by-side. For more complex cases – say, where home loans and business loans are already running – you might need a broader services review to align all your EMIs instead of looking at LAP in isolation.
Don’t Ignore The LAP Processing Fee And Other Upfront Charges
When you’re focused on interest rate and tenure, LAP processing fee often feels like a minor one-time cost. It isn’t. Between processing fee, legal and valuation charges, technical verification, and documentation costs, the upfront cash you pay to start the loan can be meaningful.
On paper, some lenders may show a lower headline rate but recover the margin through higher processing charges or non-refundable login fees. If you exit the loan early through a balance transfer or a prepayment, these upfront costs matter even more, because you’ve paid them for a shorter benefit period.
Always ask for a complete list of upfront charges, including taxes, before you apply. If a lender won’t share a clear charge sheet, treat that as a red flag. Transparent lenders are usually comfortable explaining every rupee you’ll pay before disbursal.
Key Loan Against Property Charges To Compare
Total cost isn’t only about EMIs. Make a simple table of loan against property charges for each lender: processing fee, legal/valuation, documentation, administrative charges, and any mandatory insurance bundled with the loan. You’ll often find that an apparently cheap offer turns expensive once you add these.
Also remember ongoing costs like annual statement charges or account maintenance fees. These are small on their own but can add up over a long tenure. Banks and HFCs must disclose these in their standard charge documents, so don’t hesitate to ask for them.
Compare The True Total Cost, Not Just EMI
Once you have rate, LTV, tenure, and fees, you can start comparing the true total cost of each offer. This is where many borrowers in India change their first choice, because the cheapest-looking EMI isn’t always the most economical loan.
For each shortlisted offer, calculate the approximate total interest plus all known fees over the chosen tenure. Then ask yourself two questions: does this structure keep my monthly cash flow comfortable, and does it give me flexibility to prepay or refinance without heavy penalties.
Some offers look slightly costlier on day one but give far better flexibility through lower foreclosure charges or more favourable part-prepayment terms. For example, if you’re planning to use future bonuses or business profits to reduce the loan aggressively, that flexibility can matter more than a small difference in headline rate.
How To Compare LAP Offers When You Already Have Loans
If you’re already servicing home loans or business loans, it’s risky to compare LAP terms in isolation. A LAP EMI that looks fine on its own can stress your overall repayment capacity once you stack all obligations together.
In such cases, it helps to take a portfolio view. Advisory setups that work on both home loans and business funding, such as those offering home loan strategy optimisation, can help you balance your property-backed borrowing instead of treating each loan as a separate decision.
Factor In Purpose, Risk And Exit Strategy
Two borrowers with the same property value and income can still need very different LAP structures. Someone using LAP for short-term working capital has a different risk profile from someone funding a child’s education or consolidating multiple loans.
When you compare loan against property offers, ask three practical questions: what is my main purpose, how stable is my income, and what is my likely exit route. If your purpose is inherently long term, you may accept a slightly longer tenure for safety. If it’s short term, you may focus on lower charges for early closure.
Borrowers using LAP for business growth can also benefit from reviewing business loan working capital planning at the same time. That way, you don’t overload your property with debt when a more flexible working capital structure might serve part of the need.
Conclusion
Comparing LAP offers properly means looking past the sales pitch and checking rate structure, LTV, tenure, charges and your own exit plan together. When you compare loan against property options this way, the right answer for you in India becomes far clearer.
If you’d like a second set of eyes on your LAP decision, ss finadvisory can help you weigh offers in detail against your cash flow and long-term goals, so your property works for you instead of the other way round.
Frequently Asked Questions
Q1. How do I compare loan against property interest rates from different banks?
Ans: Start by asking each lender for the benchmark rate, the spread they’re charging you, and how often the rate can reset. Then compare the effective rate over the first year using the same tenure and EMI. Also check if there are conditions under which your rate can be increased beyond normal benchmark changes.
Q2. What is a good LTV ratio for a LAP in India?
Ans: A “good” LTV ratio depends on your risk comfort and cash flow, but many borrowers prefer not to stretch to the maximum LTV limit offered by lenders. Staying a little lower keeps EMIs more manageable and leaves some room on the property for future borrowing if needed. Always weigh LTV against purpose, income stability and repayment plans.
Q3. Which is more important to compare in LAP offers: tenure or interest rate?
Ans: Both matter, but in different ways. Interest rate drives how much you pay for every rupee you borrow, while LAP tenure shapes how long you carry the debt and how high the EMI feels each month. Compare a few combinations of tenure and rate, then pick the option that keeps EMI comfortable without pushing total interest unreasonably high.
Q4. How do LAP processing fee and other charges affect total cost?
Ans: LAP processing fee, legal and valuation charges, and documentation costs are paid upfront, so they increase your total cost from day one. If you plan to prepay or refinance the loan within a few years, high upfront charges can make a seemingly attractive rate less competitive. Always add these fees to your interest outgo when comparing offers.
Q5. Can I change my LAP tenure later if my income increases?
Ans: In many cases you can reduce tenure or increase EMI later, but it depends on the lender’s policies. Some allow flexible part-prepayments that automatically shorten tenure, while others may need a formal restructuring or even a balance transfer. Ask about future tenure changes before you sign, so you know how easy it will be to close the loan faster.
Q6. How do I compare loan against property offers if I already have a home loan?
Ans: Look at your combined EMI burden and not just the LAP on its own. Factor in home loan interest, remaining tenure, and any loan against property charges that apply if you use the same property as security again. Many borrowers review their home loan structure alongside the new LAP to keep overall repayments sustainable and protect long-term goals.