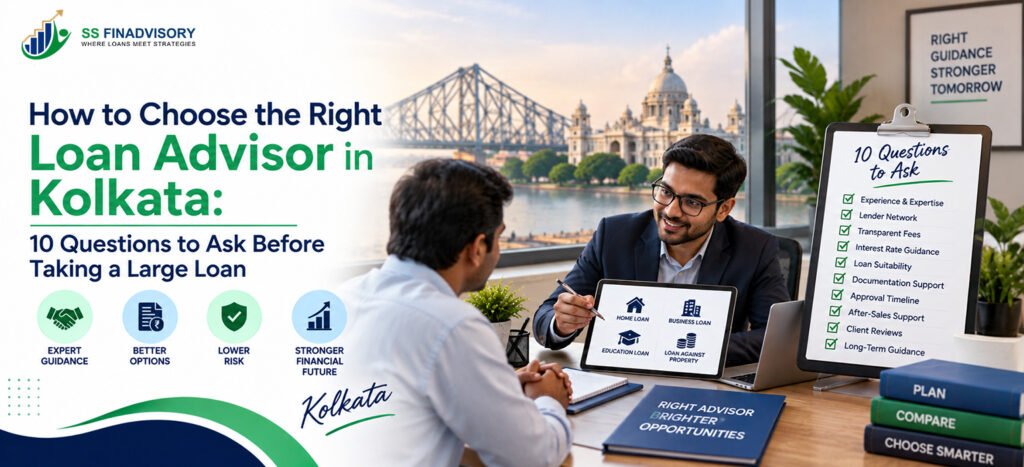
Searching for a reliable loan advisor in Kolkata usually means one thing: you’re about to take a big loan and you’re not fully confident about the fine print, bank choices or long-term impact on your cash flow. That’s exactly when the right expert can save you lakhs over the life of the loan – and the wrong one can quietly lock you into an expensive mistake.
Maybe you’re planning a home purchase, refinancing, or using property for business funding. You’ve spoken to a bank relationship manager, heard three different “best options”, and now you’re not sure whom to trust. This guide walks you through 10 sharp questions to ask any advisor before you commit, so you can separate genuine advice from sales talk in the Indian lending market.
Why The Right Loan Advisor Matters For Big Decisions In India
A large loan is not just an application form and a sanction letter. It’s a long-term financial commitment where a small difference in rate, fees or structure can change your monthly budget for years.
A good loan consultant Kolkata will go beyond “get the maximum eligibility” and instead help you match loan amount, tenure and EMI to your real-life goals – kids’ education, business plans, retirement and risk appetite. That’s the kind of thinking you’re looking for.
Question 1: Are You A Bank Agent Or A True Advisor?
This is the starting filter. Ask clearly who pays them and how broad their lender panel is. Someone tied to one or two banks will naturally push those products, even when another lender is better for your profile.
A genuine loan advisor in Kolkata should be comfortable comparing multiple banks and NBFCs for different scenarios, explaining why one suits a salaried IT professional and another fits a self-employed trader, instead of defending only one institution every time.
Question 2: What Types Of Loans Do You Specialise In?
Loans are not all the same. Home loans, loan against property, working capital loans, balance transfers – each behaves differently and has its own traps.
If you’re buying a house, you want a home loan advisor Kolkata who lives and breathes property-linked credit: how banks view different builders, what can delay disbursement, and how rate resets work after a few years.
Question 3: How Will You Decide The Right Loan Structure For Me?
Most people think only about the rate. An experienced advisor thinks in terms of total cost, risk and flexibility. Ask them exactly how they’ll recommend tenure, EMI level and fixed vs floating choices.
For example, some advisors use a structured approach similar to home loan strategy optimisation, where they map your income growth, savings habits and future goals before locking in the structure. Listen for that kind of process, not generic “we’ll get you the lowest rate” lines.
Question 4: How Do You Get Paid, And What Will I Pay You?
Compensation is where conflict of interest usually hides. Ask your loan consultant near me prospect to break this down in simple language: what they earn from the bank, what they charge you, and when it’s payable.
A clear conversation on fees upfront is non-negotiable. If an advisor avoids this or keeps saying “don’t worry, we’ll manage”, expect surprises later in the form of extra charges or subtle pressure to take a loan that’s more profitable for them than for you.
Question 5: Which Parts Of The Process Will You Actively Handle?
Some advisors just connect you to a bank RM and disappear. Others actively guide documentation, application, negotiation and post-sanction review. You want the second type for a large, complex facility.
A good financial advisor Kolkata should be able to tell you, step by step, where they step in – for example, reviewing the sanction letter for hidden charges, aligning EMI dates with your cash flow, and helping you prepare for property valuation or income assessment.
Question 6: Can You Show Me How This Loan Affects My Long-Term Plan?
Large loans don’t live in a vacuum. They sit alongside SIPs, insurance, kids’ fees and business commitments. Ask how the advisor will help you see the full picture, not just the EMI calculation.
If they bring in concepts like prioritising high-cost loans for faster prepayment or planning future balance transfers in advance, that’s a sign they think like a planner, not a middleman. This becomes even more important when a home loan consultant Kolkata is guiding you on a 15–25 year commitment.
Question 7: What Hidden Or One-Time Costs Should I Budget For?
Processing fees are only the beginning. There are legal charges, valuation fees, documentation charges, insurance premiums tied to the loan, and potential prepayment or foreclosure charges depending on the product type.
A serious advisor will walk you through a total cost breakdown. Tools and frameworks similar to those used when people compare loan against property offers can be adapted for home and business loans as well, so you see the real cost line by line.
Question 8: What Risks Am I Taking That Most Borrowers Miss?
This is the question that separates sales talk from genuine guidance. Ask them to point out risks specific to your profile: variable income, heavy existing EMIs, under-construction property, floating rate cycles.
Good loan advisory services Kolkata will also flag softer risks most people ignore: strain on family cash flow if bonuses don’t materialise, impact of a business slowdown, or how rate resets can quietly raise EMIs after a few years.
Question 9: How Will You Support Me After The Loan Is Disbursed?
Many borrowers discover painful surprises only later – rate hikes, missed reset benefits, or better offers from other banks. Ask what kind of post-disbursal support the advisor provides and for how long.
Ideally, they should help you review your loan periodically, similar to how structured LAP advisory looks at loan against property over time, not just at sanction. Post-disbursal guidance can make the difference between just having a loan and actually managing it well.
Question 10: Can You Share Real Examples Of Clients Like Me?
No need for names or private details, but they should be able to describe a few situations similar to yours – a first-time home buyer in Kolkata, a small business owner pledging property, or a salaried couple planning to prepay aggressively.
Listen for specifics: how they handled documentation issues, negotiated terms, or restructured EMIs when income changed. Vague “we have many happy clients” answers don’t tell you anything.
Red Flags When Choosing A Loan Advisor In Kolkata
As you ask these questions, watch for patterns in their responses. Overpromising is a big warning sign: guaranteed approvals, guaranteed lowest rate, or promises that sound too smooth given how lenders in India actually work.
Another red flag is constant pressure to “move fast before the offer expires” without giving you space to read the sanction letter or compare options. Quality advisors are confident enough to let you think and, if needed, suggest reading up on topics like business loan vs working capital loan structures before you decide.
How To Shortlist The Right Advisor
Start with three to four names from different sources – referrals, online searches and professional networks. Speak to each for 20–30 minutes using the 10 questions above as your checklist.
Pay less attention to who “sounds confident” and more to who asks you thoughtful follow-up questions about your income, future plans and risk comfort, the way a serious planner would.
Comparing Advisors On More Than Just Rate
Rates across lenders for similar profiles often sit in a narrow band. The real difference comes from structure, charges and ongoing review. So don’t pick an advisor only because they quote 0.05% lower than someone else on the first call.
Compare who has a clearer process, who talks about reducing lifetime interest, and who is ready to revisit the structure if your income pattern changes over time.
How A Structured Advisory Approach Helps
An organised advisor will often use frameworks similar to business loan and working capital planning models even for personal and property loans: mapping inflows and outflows, stress-testing EMIs and planning for prepayments.
This kind of planning mindset reduces the chance of future stress, because the loan decision isn’t made in isolation from the rest of your finances.
Conclusion
Choosing a loan advisor in Kolkata is really about choosing who you trust with one of the biggest financial decisions you’ll make in India. Use these 10 questions and the red flags as a simple filter, and you’ll quickly see who is selling and who is genuinely advising.
If you want structured, long-term thinking around your borrowing decisions, explore how ss finadvisory approaches property and business loans, then have a frank conversation before you sign anything.
Frequently Asked Questions
Q1. How do I verify if a loan advisor in Kolkata is genuine?
Ans: Start by asking about their registration details, the lenders they work with and how they get paid. Check their website, client reviews and how transparently they explain fees and risks. A genuine advisor will be comfortable putting key explanations and commitments in writing.
Q2. What is the difference between a loan advisor and a loan consultant Kolkata?
Ans: In practice, both terms are often used for professionals who help you choose and apply for loans. The real difference lies in approach: some only focus on getting approval, while others work more like planners, helping you think through structure, long-term cost and future prepayment options.
Q3. How can a home loan advisor Kolkata help me save interest?
Ans: A good advisor can guide you on choosing the right tenure, EMI, and fixed vs floating rate mix based on your income and goals. They can also suggest strategies like planned prepayments or timely balance transfers when rates or your situation change, which can significantly cut interest over the years.
Q4. Should I meet a loan consultant near me or is online advice enough?
Ans: For straightforward, smaller loans, online advice and phone calls are often sufficient. For large home or property-backed loans, meeting a loan consultant in person can help you discuss documentation, property issues and long-term plans in more detail, especially if local knowledge of Kolkata projects and lenders matters for your case.
Q5. Can a financial advisor Kolkata help with both investments and loans?
Ans: Many financial planners do handle both sides, but not all are equally strong on credit. If you want one person to advise on investments and loans, ask specific questions about their experience with home loans, loan against property and business finance before you rely on their recommendations.
Q6. How do I choose between a home loan consultant Kolkata and going directly to my bank?
Ans: Going directly to one bank limits you to that bank’s products and policies. A specialised home loan consultant can compare multiple lenders, spot hidden charges and help you negotiate better terms based on your profile, which is especially valuable for large-ticket home purchases in India.