You started searching for “business loan vs working capital loan” because cash is tight somewhere in your business. Maybe sales are fine, but vendors want faster payment, or a new project needs money before the client pays. The problem isn’t the jargon, it’s picking the right funding option without locking yourself into the wrong EMI for years.
If you run a small or mid-sized business in India, you’ve probably been offered both a term business loan and some form of working capital limit. They sound similar, banks sell both aggressively, and many owners just sign whatever gets approved first. That’s usually where repayment stress begins.
Business Loan Vs Working Capital Loan: Quick Difference
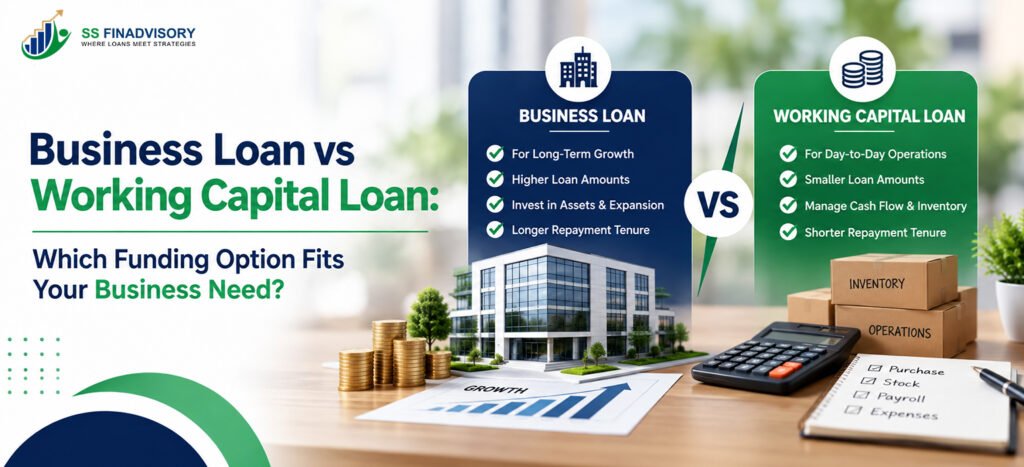
A standard business loan is normally a fixed amount with a defined tenure and EMI. You use it for a specific goal – a new machine, a warehouse, a shop fit-out, sometimes even to consolidate older loans. A working capital loan (including overdrafts and cash credit) is designed to plug day-to-day gaps in cash flow, not to sit on your balance sheet for long periods.
One practical thumb rule: if the benefit of the spend stays in your business for many years, a term loan often fits. If the money circulates within a few months – stock, receivables, operating expenses – you usually look at working capital finance instead.
When A Business Loan Fits Better
Think of a business loan as long-term money tied to a long-term asset or goal. It makes sense for expansion that changes the shape of your operations: adding a new production line, opening a second outlet, or investing in heavy equipment that will earn for years.
Many owners in India also use an SME business loan to clean up messy borrowing – closing high-cost personal loans, credit card dues and informal borrowings, and replacing them with one structured term facility.
The advantage is predictability. You know the EMI, you know the tenure, and you can plan cash flow accordingly. The trade-off is flexibility. Once the loan is disbursed, interest runs on the full amount from day one, even if you don’t use all the funds immediately.
For complex decisions that involve both expansion and existing debt, some businesses go beyond simple bank offers and work with specialists in business loan and working capital planning to structure the mix more carefully.
When A Working Capital Loan Is The Smarter Choice
A working capital limit is meant to breathe with your business cycle. Textile traders, pharma distributors, seasonal manufacturers – anyone with large receivables or inventory swings – usually depend on this form of business financing even more than on term loans.
Used well, working capital limits prevent those desperate moments where you delay salaries or vendor payments because one big client is late. The right limit size and structure can stabilise operations without forcing you into unnecessary long-term debt.
Problems start when owners use working capital limits like term loans – drawing the maximum and leaving it fully used throughout the year. At that point, interest outgo climbs, and the facility loses the very advantage it was designed to offer.
If you’ve already reached that stage, detailed advice such as in this guide on working capital loan restructuring can help you understand options to reduce interest and free up limits.
Key Factors To Compare: Business Loan Vs Working Capital Loan
When clients ask which is better, I rarely answer before we walk through a few specific points. These usually decide the right mix more clearly than headline interest rates.
1. Purpose And Tenure Of Use
If you plan to repay from future profits over several years, a term-based business loan normally works better because it matches the repayment to the life of the asset or project.
If the money will rotate every few months, as in funding stock or credit to customers, a limit-based working capital loan is usually safer. Stretching short-term needs into long-term EMIs is a classic cause of cash flow stress.
2. Security And Collateral
Banks often expect collateral, sometimes property, for a larger business funding option. Unsecured term loans exist, but they may come with tighter eligibility and higher pricing compared to secured lines.
Working capital limits are usually backed by current assets – stock and receivables – though for higher limits, lenders may still ask for property or other collateral comfort.
3. Interest Cost And Usage Pattern
Business term loans are generally priced with a fixed or variable rate on the full disbursed amount, so interest keeps running even if cash sits in your account. That can hurt if the project spends are staggered and you rushed to take the loan early.
With many working capital arrangements, interest is charged on the amount you actually draw, not the full sanctioned limit. If your utilisation fluctuates, this structure can be cheaper over a year.
Common Mistakes Indian Businesses Make With Loan Choices
Most mistakes don’t come from picking the wrong product label. They come from mixing short-term and long-term needs casually. Founders take a long-tenure SME business loan for temporary cash gaps, or they park permanent needs inside limits that should really stay fluid.
Another frequent issue is ignoring how new EMIs interact with existing home loans, personal loans or property loans. Many owners in India only realise the strain when a slower sales quarter arrives and servicing all obligations together becomes difficult.
Some also assume their bank will “adjust later” if the structure doesn’t work. In practice, restructuring is possible but rarely simple. Carefully designed loan-against-property advisory and business planning up front can save years of stress.
If you want a clearer picture of how your working capital actually behaves through the year, this detailed guide on calculating the right working capital requirement is a strong starting point.
How To Decide: Simple Practical Checklist
Start with your balance sheet and cash flow, not with the lender’s product brochure. List why you need funds, how long the need will last, and from where repayment will come. Only then match a loan type to each piece.
For a longer project, you might split funding: part term business loan for equipment and part limit for raw material and operating costs. The mix matters more than the label of any single product.
4. Map Needs To Funding Buckets
Group your requirements into three buckets: one-time investments, recurring operating gaps, and “safety buffer”. Long-tenure funds should mostly sit in the first bucket. The second bucket usually deserves working capital finance, sized properly based on your real business cycle.
That separation alone stops many owners from loading every requirement into one single loan and hoping it works itself out.
5. Stress-Test Your EMIs
Before finalising any business financing, run scenarios where your monthly inflows drop for a quarter – delayed payments, lost orders, or seasonal slowdown. If EMIs still look manageable with some margin, the structure is probably safer.
If even a modest dip in revenue makes the plan uncomfortable on paper, consider reducing the loan size, increasing tenure carefully, or shifting some needs into a more flexible facility.
When To Get Professional Help
There’s a point where DIY comparisons stop working. Multiple facilities with different tenures, property loans in the background, lenders pushing top-ups – that’s when having someone look at the full picture can save you from expensive trial and error.
Specialised services for business owners can help you review existing loans, assess true working capital gaps, and build a funding plan that doesn’t collapse in a slower year.
If your working capital account stays near its limit throughout the year or you’re juggling many EMIs already, that’s a clear sign to pause fresh borrowing decisions and get an independent view first.
Once the right structure is set up, you’ll find day-to-day decisions easier: which orders to accept, how much credit to offer customers, when to negotiate better terms with suppliers, and how to pace your own growth.
Conclusion
Choosing between a business loan vs working capital loan is really about matching money type to money need, not about which product sounds more attractive in a sales call. For Indian businesses, that alignment often decides whether growth feels exciting or exhausting.
If you’d like an experienced eye on your existing loans and funding gaps in India, ss finadvisory can help you structure a more balanced mix so that future borrowing decisions support your plans instead of restricting them.
Frequently Asked Questions
Q1. What is the main difference between a business loan and a working capital loan?
Ans: A business loan is usually a fixed amount repaid over a specific tenure using EMIs, ideal for long-term assets or projects. A working capital loan is generally a revolving limit meant to cover daily operational gaps in cash flow, with interest charged on the amount you use.
Q2. Which is better for a small business in India with seasonal sales?
Ans: For seasonal businesses in India, a well-assessed working capital loan often fits better, because it can expand and contract with your receivables and inventory. A term business loan may still be useful for long-term investments, but using it for seasonal gaps can lead to unnecessary long-term EMIs.
Q3. Can I use a business loan for working capital purposes?
Ans: You can, but it’s usually safer to match short-term needs with proper working capital finance instead of locking them into long-tenure EMIs. Using a term loan for temporary gaps can strain cash flow when sales slow down or payments get delayed.
Q4. How do lenders decide the limit for a working capital loan?
Ans: Lenders typically look at your past financials, stock levels, receivables and overall working capital requirement to decide the limit. They also consider your repayment history, banking pattern and existing business financing before sanctioning a line.
Q5. Is it possible to change from a working capital loan to a term business loan later?
Ans: In some cases, lenders may allow you to convert a part of your limit into a term facility or offer a separate SME business loan to regularise long-term needs. This depends on your profile, collateral and repayment record, so you should review options with your banker or a trusted advisor.
Q6. How do I decide the right mix of term loan and working capital for my business?
Ans: Start by separating long-term investments from short-term operating gaps, and then assign the appropriate business funding option to each. Many owners also take help from advisors experienced in business loan and working capital planning to test different mixes before committing, which can reduce the risk of future cash flow stress.