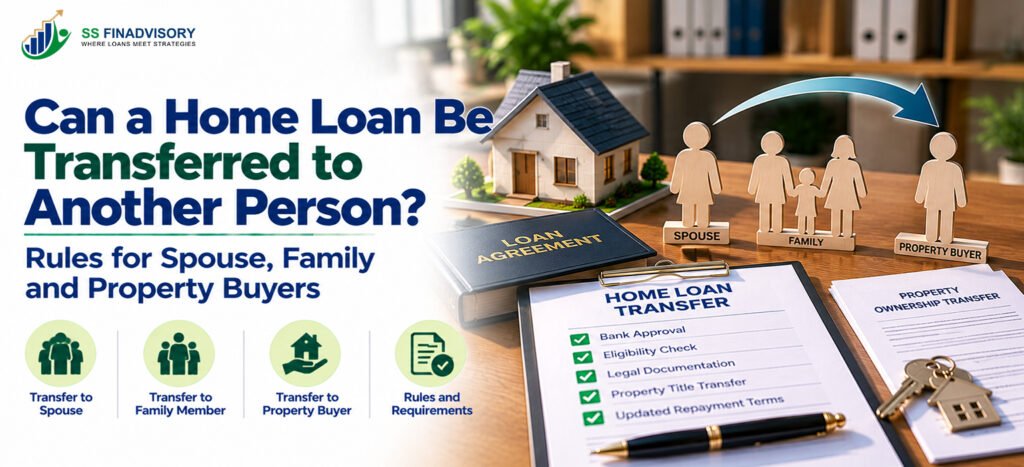
The topic “can home loan be transferred from one person to another” matters because buyers in India mix up property transfer with loan transfer and that confusion gets expensive fast. Banks treat loan transfer very differently from gifting a flat to your spouse or selling it to a new buyer, and if you get that wrong you can end up with transfer charges, tax surprises or even a rejected sale.
What follows is a plain breakdown of when a housing loan can stay with the same bank and simply change borrowers, when it needs a fresh sanction, and when transfer is not possible at all. We will walk through spouse cases, parents and children, sales to a third party, how balance transfer fits in, and when it makes sense to involve a specialist instead of negotiating it alone. If you’d rather hand this part over, it’s the kind of work our Loan against Property Balance Transfer team handles every week.
What “Transfer” Of A Home Loan Really Means
Before you plan anything, you need to separate three ideas in your head: changing ownership of the property, changing the name on the loan, and refinancing the loan with a new lender. Most people use “transfer” for all three, which is how you end up with a seller promising the buyer that the bank will simply shift the EMI to their name.
From the bank’s point of view, your existing loan is a contract based on one borrower’s income, credit history and security. If they agree to move that liability to someone else, they do it only after a fresh assessment, very similar to a new home loan eligibility checkeven if the flat is the same.
When Can Home Loan Be Transferred From One Person To Another
The direct answer is that can home loan be transferred from one person to another depends entirely on the bank’s policy and the profile of the incoming borrower. Indian lenders usually allow it only in a few structured scenarios, and they reserve the right to insist on a new loan instead of modifying the old one.
Most banks will look at transfer requests only in cases like adding or removing a spouse as co borrower, family settlements where ownership is shifting within close relatives, and sale of the mortgaged property to a buyer who qualifies for a new loan from the same bank. Even then, they run full income checks and can say no without giving you a detailed reason.
Adding Or Removing A Spouse On The Home Loan
For married borrowers, the first pain point is usually marriage, divorce or death, when the question of changing the loan name comes up. Lenders in India are relatively flexible on spouse cases because the risk profile is still within the same household and the property ownership often stays shared.
If you got married after the loan and now want your spouse added, banks often process that as a modification of the existing loan document, not as a fresh sanction. They will check your spouse’s KYC, income proof and credit report, and sometimes they may use the combined income to increase the eligible amount in a top up, similar to how a “Home Loan for Joint Applicants” works.
Transferring Solely To A Spouse
Transferring the entire loan to a spouse’s name typically comes up in separation or when the original borrower is moving abroad. Banks will agree only if the spouse independently qualifies for the full outstanding amount under their income and credit norms, and the property title is updated in line with that change. It’s one of the first things we look at in any income proof for Loan against Property project.
In divorce settlements, the court order helps but doesn’t bind the bank; they still need to be satisfied that the continuing borrower can service the EMI. We see many cases where the settlement says the husband will clear the EMIs, but the bank continues to treat both ex spouses as liable because nobody approached them formally to restructure.
Transfer Within Family: Parents, Children And Siblings
Family transfers get messy because people assume “same family” means the bank will be relaxed. From the lender’s chair, a son is still a separate borrower with his own risk, even if he’s already co owner of the flat.
Where parents have taken the loan and are ageing or retiring, children often want the EMI to move formally to their name. That discussion is very similar to a fresh loan sanction, and the bank can be stricter if the title is in the parents’ name, which is exactly the kind of case discussed in the post “Home Loan for Property in Parents’ Name“.
Gift Deeds And Family Settlements
If the property is being gifted to a child or sibling while the loan is still active, the bank’s consent is mandatory before you register any transfer deed. Often they’ll insist that the incoming owner either joins as co borrower or takes a fresh loan, clears the old account and then completes the transfer. We run into this a lot when clients come to us for co applicant Loan against Property.
Where multiple siblings inherit a charged property, it’s common for one person to take over both ownership and the loan. In that case, the bank will run income checks, ask for NOCs from other heirs and only then restructure the loan into a single name.
Sale To A New Buyer While Loan Is Running
When you sell a mortgaged flat, you’re really asking the bank to cooperate so that their charges are cleared on time and the buyer gets clean title. That can happen in two ways, and mixing them up is where deals fall apart. Getting it right early saves a lot of rework, and it’s a regular part of our Home Loan for first time buyers work.
In the first option, the buyer takes a new loan from the same bank, the bank uses that disbursal to close your outstanding and then registers a new mortgage in the buyer’s name. On paper this looks like a transfer but legally your old loan ends and the buyer’s new loan begins, similar to how a home loan balance transfer consultant would close one bank and open another.
Buyer Taking Loan From Another Bank
If your buyer’s loan is from a different bank, your existing lender will give a foreclosure letter and a list of documents to be released on payment. The buyer’s bank disburses to your bank, collects the original papers and then marks its own charge, so there is no direct transfer of your loan to the buyer.
Sellers sometimes promise that the buyer can “take over” their cheap fixed rate, but banks rarely allow that. It’s safer to assume that the buyer will get the rate and terms available to them now, just as someone comparing “Home Loan Balance Transfer vs Prepayment” has to work with present offers, not old ones.
Transfer Versus Home Loan Balance Transfer
A lot of borrowers confuse personal transfer with balance transfer. In a balance transfer, the borrower stays the same, the property stays the same, only the bank changes, and the goal is to reduce home loan interest rate and sometimes the EMI.
If you simply want better pricing or lower EMI, you don’t need another person to step in. You just compare offers, check processing fees, weigh top up options and decide whether moving to a new lender or renegotiating with your current one is better, something we covered in depth in “Fixed vs Floating Home Loan”.
When A Balance Transfer Contains A Name Change
Occasionally, families try to combine a personal transfer with a balance transfer, for example shifting a loan from father to son while also changing the bank. In practice, the new lender underwrites a completely fresh loan in the son’s name, closes the father’s account and keeps the property as security, so the father’s earlier loan contract ends. If you’d rather hand this part over, it’s the kind of work our Loan against Property consultant Kolkata team handles every week.
This can work well when the incoming borrower has stronger income or credit and can access better pricing, but it also means fresh processing fees, legal checks and valuation costs, so it’s not a quick fix for a casual name change.
When You Need Professional Advice On Loan Transfers
Complex transfers sit at the intersection of family law, tax and bank policy, which is where an experienced home loan advisor Kolkata can save you from expensive mistakes. Banks will explain their own process, but they won’t guide you on how that interacts with your family arrangement or long term tax impact.
If you’re in a city like Kolkata and need someone to handle paperwork, chase approvals and negotiate, working with a strong home loan agent in kolkata network helps speed things up far more than calling random sales numbers at different banks.
Specialists For Interest Cost And Restructuring
Borrowers looking to clean up old joint loans or split liability after a family event probably care about two things: legal clarity and total interest cost. A good loan advisor in Kolkata should be able to model both, and tell you whether you’re better off doing a full takeover in one name or keeping a co borrower structure for a few more years.
If the main trigger for moving names is to cut EMI or total payout, it may be smarter to work through a home loan balance transfer consultant and restructure the loan on better terms instead of forcing a risky personal transfer.
Conclusion
The real answer to “can home loan be transferred from one person to another” is that banks allow it only in narrow, well documented situations, and they treat each case as a fresh credit decision. Spouse additions, family takeovers and buyer loans over an existing mortgage are all possible, but the process is slower and stricter than most families expect. It’s one of the first things we look at in any best Home Loan bank project.
If you’re planning a name change or sale around an ongoing loan, get clear on the bank’s policy early, speak to a professional if the structure is complicated, and only then commit to dates or settlement terms with the other party, and that is exactly where ss finadvisory can step in if you need structured guidance.
Frequently Asked Questions
Q1. Can I transfer my home loan completely to my wife’s name?
Ans. You can transfer a home loan entirely to your spouse only if the bank agrees and your spouse independently qualifies for the full outstanding amount. The lender will reassess income, credit score and property ownership before restructuring the loan. Court orders or family agreements alone are not enough if the bank is not comfortable with the risk.
Q2. Can a buyer take over my existing home loan when purchasing my flat?
Ans. A buyer usually cannot just step into your loan contract as it is. Most banks close your existing loan and sanction a fresh loan to the buyer based on their income and eligibility. The practical effect may look like a transfer, but legally it is a closure and a new loan, with new terms and conditions.
Q3. Is it possible to add my parents as co borrowers after the loan is disbursed?
Ans. Some banks allow adding close family members such as parents as co borrowers, but policies differ. The bank will want to see that adding them improves or at least does not weaken the risk profile. They will update loan documents and may ask for revised property ownership if they expect the co borrower to have a stake in the house.
Q4. What is the difference between transferring a loan and doing a balance transfer?
Ans. Transferring a loan usually refers to changing the borrower while keeping the same bank and property. A balance transfer means the borrower and property stay the same but the loan moves to a new lender to get better terms. In paperwork terms, both involve closing one contract and signing another, but the credit assessment focus is different.
Q5. Will my interest rate stay the same if another person takes over my home loan?
Ans. In most cases the incoming borrower will get the rate pattern applicable to them and to that product on the date of restructuring. Banks are not obliged to continue your old fixed or promotional rate for a new borrower. You should assume fresh pricing and evaluate if a new loan or balance transfer gives better value.
Q6. Do I need a lawyer for transferring a home loan within the family?
Ans. It is wise to consult a property lawyer when ownership is changing hands within the family while a loan is active. The bank will handle their own documentation, but you need clear gift deeds, release deeds and succession papers to avoid future disputes. A lawyer can also align your family documents with what the bank requires.