If you run an MSME in India, you already know a working capital loan for MSME can be both a lifeline and a headache. The funds arrive when you need them, but a year later you realise the EMI schedule or drawing power never really matched your cash flow cycle.
The gap shows up as constant limit shortages at month-end, interest on idle balances in the middle of the month, and tense conversations with your banker. This article is about fixing that by structuring borrowing around the way cash actually moves through your business, not around a banker’s template.
Start With Your Real Cash Flow Cycle, Not The Bank Form
Most MSME owners can tell you their annual turnover in seconds. Very few can tell you their true cash conversion cycle. That’s the number of days from paying your suppliers to finally collecting from customers.
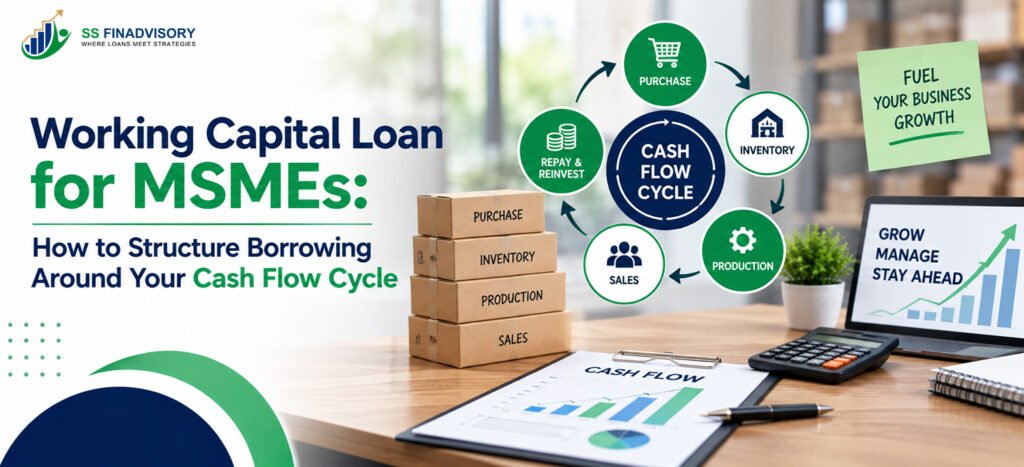
Before you even think about an MSME working capital loan, map that cycle on a simple timeline. List out: when you pay advances or buy raw material, how long production takes, how long goods sit as stock, your average credit period to customers, and how many days customers actually take to pay. The idea is to see where the cash gaps are, week by week, not just on an annual P&L.
A practical way to do this is to build a 13-week rolling cash flow. Put expected inflows on the right dates of invoice collections, and outflows on the dates salaries, rent, GST, EMIs and supplier payments fall due. Once you’ve done this for one full cycle, the size and timing of your funding need becomes obvious.
Match Product Type To The Stage Of Your Cycle
Too many businesses take a single generic business loan for MSME and then try to force-fit it to every need: stock, salaries, even a one-time machinery upgrade. That’s usually why interest costs feel permanently high and limits feel permanently wrong.
Your short-term needs split broadly into two buckets. First, recurring working capital for raw material, work-in-progress and finished goods. Second, temporary spikes like seasonal stocking, a large one-off order, or a delayed bulk payment from a key client. Each of these deserves a different funding product and different repayment pattern.
Recurring needs are normally better suited to lines that move with sales, such as cash credit or overdraft against stock and receivables. Spikes can be handled with short-tenure working capital finance or invoice-backed limits that run down as specific bills are paid. The mistake is using long-term EMIs to plug short gaps; that’s how you end up repaying for three years for a cash crunch that lasted three months.
How Banks Think About Cash Flow Based Lending
Traditional lenders still look heavily at collateral, but for many MSMEs the real story sits in bank statements and GST returns. When a bank says it is doing cash flow based lending, what it usually means is that it’s looking at your actual daily credits, seasonality and client concentration, not just last year’s balance sheet.
For you, that changes where you should focus. Clean, regular banking of all sales, consistent routing of major expenses through the main account and reasonable discipline in drawings all help present a stable pattern. Irregular transfers, heavy cash dealings and multiple scattered accounts do the opposite.
If you’re planning to restructure or seek a fresh SME loan, start six months early by tightening how money moves through your accounts. A clear pattern of sales and collections often gives you more negotiating strength on both limit and pricing than a slightly higher profit on paper.
Structuring A Working Capital Loan For MSME Around Inflows
Once you understand your cycle, structuring a working capital loan for MSME becomes a practical exercise, not a guess. There are four questions that matter: how much of the requirement is permanent, how much is truly seasonal, how concentrated your customers are, and how predictable your inflows actually are.
Permanently blocked funds, like minimum raw material or safety stock, often justify a core limit that stays for the full year. Seasonal spikes can sit on a separate sub-limit with a clear start and end. If your collections are lumpy because two or three large buyers dominate, your repayment schedule has to sit a few days after those invoice due dates, not neatly on the 1st of the month.
For many owners, this is where an external view helps. A specialist advisory focused on business loan working capital planning can help you differentiate between what must be funded all year and what can be covered by better collection discipline or supplier terms.
Choosing Between Limits, EMIs And Hybrid Structures
Every MSME business funding conversation eventually reaches the same debate: should I take a limit or a term loan? In reality, most growing firms need a mix. Limits are flexible but demand more discipline; term loans are predictable but can trap you into paying interest far beyond the period you actually used the money.
One approach that often works is to fund longish, stable gaps with a small term facility and short, order-linked gaps with a drawing limit. A clear internal rule that term loans are only for permanent working capital and asset-backed needs stops the slow creep of term borrowing for every cash crunch.
Link Repayment Dates To Your Collection Behaviour
Most MSMEs agree to EMI dates based on what feels convenient, not on what the 13-week cash flow actually shows. That’s how EMIs start bouncing right after a big client asks for an extra week to pay. Your working capital finance structure should tolerate minor collection delays without pushing you into penalties every month.
When you negotiate, take your actual collection pattern to the table. Show that invoices from one cluster of customers clear in the first half of the month and the others in the second half. Asking for EMIs or interest debits to hit a few days after these clusters, instead of blindly on the 1st, can make a meaningful difference to your stress levels.
Using Property-Backed Limits Without Over-Borrowing
Many MSMEs in India end up using property-backed limits to fund working capital, because that’s the asset they actually have. Done thoughtfully, this can give you a higher limit and better pricing. Done casually, it can lock family property against a loan that isn’t really sized to your cycle.
The key is to separate decision-making on security from decision-making on limit. Just because the property value allows a high sanction doesn’t mean your actual working capital requirement justifies drawing all of it. Your 13-week cash flow should still be the anchor for how much of that facility you actually use.
Where property is involved, taking expert help from someone who understands loan against property structures and how they interact with working capital can save you from tying up too much security for too long.
When To Restructure An Existing Working Capital Setup
If you’ve already got limits and loans running, the right time to rethink them is not after multiple cheques have bounced. The early warning signals are subtler. You’re regularly paying interest on large unused limits, or you’re constantly asking for ad-hoc enhancements despite rising sales.
In those cases, a fresh view of your structure can help. Reviewing how your current limits sit against your sales cycle, and how your EMIs line up against actual inflows, may show that you need to shift some of your borrowing from term to limit, or vice versa. A planned change is always better than a hurried one forced by temporary stress.
Planning For Growth Without Getting Trapped
MSME owners often underestimate how much extra working capital growth will eat before extra profits show up. If you’re forecasting a sharp jump in sales, the first question is not how much profit that will add, but how much extra stock, receivable days and production capacity it requires.
Before signing for more debt, run a simple “growth scenario” through your cash flow sheet. If sales grow by the percentage you expect, how many extra rupees get tied up in stock and receivables, and for how many weeks? That tells you how much extra funding you genuinely need, and whether your current SME loan structure can stretch to support it.
If you find the gap is wider or longer than your present banking setup can safely carry, explore smarter structures before pushing for limit hikes. Reading up on topics like working capital requirement calculation makes you a sharper counterpart across the table from your banker.
Don’t Ignore Interest Cost While Chasing Convenience
Many MSMEs accept higher pricing because the facility feels convenient or the documentation looks simple. Over a few years that quiet cost adds up, especially if your limits are not right-sized. Paying interest on idle balances or long-term loans used for very short gaps is just money left on the table.
If you suspect your structure has become expensive, study strategies to reduce interest without cutting your limit, such as those discussed in guides on optimising working capital interest. Often the answer lies in reshaping the structure around your cycle, not in constantly asking for a lower rate.
Conclusion
Structuring a working capital loan for MSME around your real cash flow cycle is less about clever products and more about honest visibility. Once you see, week by week, where money goes out and comes back in, the right mix of limits, EMIs and tenures in India becomes much easier to decide.
If you’d like an experienced view on that mapping and on your current funding setup, ss finadvisory has resources and advisory services that can help you ask sharper questions before your next banking discussion and align your borrowing to how your business actually runs.
Frequently Asked Questions
Q1. How do I decide the right size of a working capital loan for my MSME?
Ans: Start with a 13-week cash flow that maps expected inflows from customers and outflows like salaries, rent, GST and supplier payments. The biggest cumulative gap on that sheet is a good starting estimate. From there, refine the number based on seasonality and how much your suppliers and customers are willing to stretch their credit terms.
Q2. What is the difference between an MSME working capital loan and a regular term loan?
Ans: A term loan usually comes with a fixed EMI and a defined tenure, often suited for assets or permanent funding needs. An MSME working capital loan is typically structured as a limit tied to stock and receivables that you draw as needed and repay as customers pay you. Using term loans for short, revolving gaps can make you pay interest far longer than you benefit from the funds.
Q3. Can I use a property-backed loan for working capital finance in my business?
Ans: Many MSMEs use property-backed facilities to support working capital finance when they lack other security. The key is to size the drawing based on your cash flow cycle, not just on the value of the property. Treat the higher sanction as flexibility, not an invitation to over-borrow, and review usage regularly as your sales pattern changes.
Q4. How does cash flow based lending help MSME business funding?
Ans: Cash flow based lending focuses on your actual bank credits, GST flows and invoice patterns instead of only the last audited balance sheet. For MSME business funding, this can sometimes support better-structured limits, especially where formal security is limited. It also rewards clean, consistent banking and transparent routing of business transactions.
Q5. Is a cash credit limit better than a small SME loan for day-to-day needs?
Ans: A cash credit limit usually suits day-to-day needs that rise and fall with sales, because you pay interest only on what you draw. A small SME loan with fixed EMIs can work for more stable gaps that don’t fluctuate much. Many growing firms use a mix, keeping term borrowing for long-term or permanent needs and limit-based facilities for variable working capital.
Q6. How should MSMEs in India prepare before meeting a banker for working capital?
Ans: Prepare a clear 13-week cash flow, a simple summary of your cash conversion cycle and realistic projections for the next year. Clean up your bank statements by routing all major business transactions through the main account for a few months. This preparation helps you explain your working capital finance needs with confidence and makes it easier for the lender to structure the right facility.