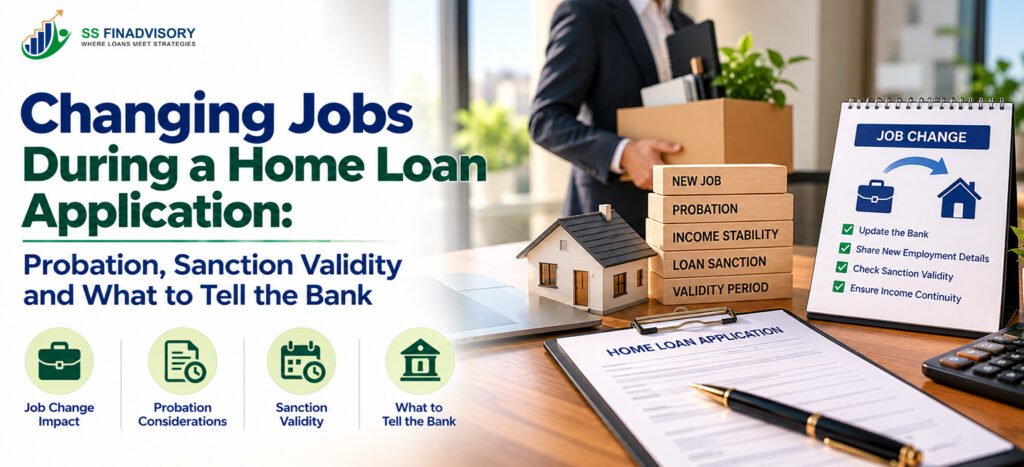
A job change during home loan process looks like a better career move to you, but to the bank it is a fresh question mark on income stability. Credit teams lend for decades, so the timing of a role change, probation or salary restructure matters much more than most buyers expect.
If you are already shortlisting properties, speaking with a home loan consultant in kolkata or comparing bank offers, you need a clear view of how a job move affects eligibility, sanction validity and disbursement. By the time you finish reading, you will know when a switch is usually safe, when it is risky and what you must tell the bank so your purchase does not get stuck.
Why Banks Care So Much About Your Employment Stability
Banks do not lend on CTC, they lend on steady net income that looks predictable over years. A sudden switch, a very variable package or a shift into a new industry creates doubt, and credit officers are trained to be conservative whenever they see doubt in a salaried profile.
For most salaried buyers, the underwriter wants continuity of work in a similar line without frequent gaps. That is why a clean home loan eligibility check starts with your last 6 to 12 months of salary credits and employer history, not with the highest CTC you have ever held or a big hike that has not yet reached your bank account.
Job Change During Home Loan Process: Which Stage Are You In
How risky a switch looks to the bank depends a lot on the stage of the loan. The same move can be harmless before login and painful if it happens between sanction and final disbursement when the builder is already chasing you for money.
If you have only taken basic advice from a home loan advisor Kolkata and have not yet filed documents with a bank, you still have room to change jobs first. Then you can apply afresh once your first new salary hits the account and your probation terms sit clearly on paper.
Before Login Or Sanction
If no application is logged in and no property is final, do not rush a sanction only to feel approved. Many buyers apply early, pick a bank, then change jobs and end up renegotiating rate, tenure or amount when they are already under pressure from a seller or broker.
Waiting till you are stable in the new role usually gives you more room to reduce home loan interest rate through proper negotiation. It also gives you time to read practical guides like Home Loan for a Resale Flat so you see how income risk and property risk sit together in the bank’s mind.
After Login But Before Sanction
Once the file is logged in with bank statements and salary slips, any change in employer or role becomes material information. Hiding it is a bad idea, because many banks reverify employment over phone and email just before signing off. If you’d rather hand this part over, it’s the kind of work our best Home Loan Bank team handles every week.
If an offer is in hand and your joining date is close, talk openly to your home loan agent in kolkata or relationship manager and ask whether the bank can hold the decision till a first salary credit. In some cases it is smarter to shift the case to a lender that is more flexible on continuity rules, especially if your old company was more stable on paper.
After Sanction But Before Disbursement
This is where most problems arise. The Home Loan Sanction Letter looks final, but it is always subject to checks at disbursement, which include a fresh employment verification and, in many banks, a quick CIBIL pull.
If you switch employers or resign in this window, the bank may put your file on hold till they see updated joining proof or at least one new salary credit. That can be a serious issue if your builder has tight payment timelines and penalties for delayed slabs, especially in a resale flat where the seller also has fixed commitments.
How Probation Periods And Role Changes Affect Your Loan
Banks are usually more worried about probation than about the job change itself. Someone on probation can be asked to leave faster than a confirmed employee, and that risk sits directly on the underwriter’s mind while approving a long term EMI.
Some lenders still approve while you are on probation with a strong brand or in a government linked entity. Others want at least three months completed or one salary credit in the new company, which is where a planner who works like a home loan balance transfer consultant can help you time the application so your track record looks cleaner.
Switch Within Same Industry Vs New Industry
Moving from one IT company to another IT company on a better role usually looks fine on paper. Moving from a stable salaried job to an early stage startup or a pure variable sales role tends to worry most credit officers because the income can swing or stop faster. It’s one of the first things we look at in any reduce Home Loan EMI project.
If you are mid process, prefer a switch that keeps you in the same industry and role type till disbursement. You can always take the riskier jump later when EMIs are running smoothly and you are not juggling builder demands along with a new probation period.
Role Change With Higher Variable Pay
Large hikes that come mostly from variable pay rarely help your loan amount in the short term. Many banks average incentives over 6 to 12 months and, if there is no track record yet, they simply ignore that variable component when they calculate eligibility.
If your main goal is a bigger property or a clean profile for a future move, a steady fixed salary can be more useful than a flashy, incentive heavy offer letter. Later, when your income pattern is set, a planner or Home Loan Interest Rate Negotiation specialist can revisit the structure and see how much room the new pay gives you with banks.
Sanction Validity, Revalidation And Fresh Eligibility Checks
Most home loan sanctions in India carry a limited validity period, often a few months, after which the bank wants to recheck income, credit and property papers. A significant job change inside that window usually forces them to reassess you as a fresh case.
If your net income has gone up and continuity looks strong, this reassessment can work in your favour. It can also be a good time to enter a negotiate home loan interest rate discussion using your improved numbers instead of accepting the original offer blindly.
Property Linked Sanctions
When the sanction is linked to a specific flat, any delay from job documentation can collide with builder demand schedules. Banks will not rush disbursement just because the builder is threatening interest or cancellation, since for them the risk always sits on your repayment capacity.
If you already know a career move is coming, align your property booking and loan timing so that large demands do not fall exactly in your probation window. This is even more important if you are looking at a project where you may need to read guidance like Home Loan Without Occupancy Certificate before you commit.
Taking A Sanction To Another Bank
Borrowers sometimes try to use a high sanction from Bank A to pressure Bank B into matching the offer. That really works only when your profile has stayed stable or improved since the first approval. We run into this a lot when clients come to us for Loan against property Balance Transfer.
Once a major job change is in play, expect the new bank to ignore the earlier sanction and recalculate from scratch. They will treat you in the same way they do for a Banks for Home Loan Balance Transfer in India comparison, where each lender judges your income on its own policy and comfort level.
What To Tell The Bank And What To Document
The safest rule is simple. If the change affects who pays your salary, how much you earn or how predictable that money is, inform the bank instead of hoping they miss it in final verification. Getting it right early saves a lot of rework, and it’s a regular part of our close Home Loan early work.
Credit teams like clean files with proper papers. Giving them updated documents early makes it easier for them to sign off and reduces the chance that your file sits in a vague wait and watch tray while your builder keeps calling and penalties keep adding up.
Documents To Keep Ready If You Switch
- Resignation acceptance email or letter from your old employer.
- New offer letter with role, fixed CTC and joining date clearly mentioned.
- First salary slip and bank statement showing salary credit from the new company.
- Revised Form 16 or updated salary breakup once available.
Once these are in place, your banker can revisit EMI and tenure options without guessing. They can also help you plan for a later home loan balance transfer vs prepayment decision when your income trail is long enough and you are thinking about interest savings.
How To Talk To The Credit Manager
Many borrowers only speak to sales and never talk to the person who actually signs off the loan. A short, clear call with the credit manager, often arranged through a loan advisor in Kolkatacan remove a lot of worry if you explain your job change properly. If you’d rather hand this part over, it’s the kind of work our Home Loan Documents team handles every week.
Explain why you are switching, how the new role is similar or stronger for income stability, and share documents upfront instead of vague promises that letters are coming soon. Underwriters relax when the story and the paperwork match and there are no surprises during verification.
Planning Career Moves Around Property Purchases
If you know a promotion, internal transfer or external switch is likely this year, plan your property search around it instead of treating both as separate tracks. The aim is to have a few months of stable salary credits in the same company and role before you sign a heavy agreement or pay a big token on a flat.
That same planning helps later when you want to use tools like a Home Loan Rate Reset check or when you read the Home Loan Balance Transfer Documents Checklist. You do not want recent job history to be the reason a better offer gets delayed or rejected.
When To Delay The Job Change
There are times when saying no to a good offer for a few months is cheaper than saying yes today. If your disbursement is close, builder demands are rigid and your new company insists on strict probation, waiting till registration or possession can protect you from extra interest and penalties. It’s one of the first things we look at in any Home Loan Interest Certificate project.
The same logic applies if you are about to complete a year with your current lender, which is often the minimum before they seriously look at a move with a home loan balance transfer consultant for a better rate or tenure. Patience here can save you more money than the hike brings in the short term.
When The Job Change Truly Cannot Wait
Sometimes there is no real choice, such as a project shutdown, health issues or relocation for family reasons. In those situations your first priority is to keep continuous income flowing, even if that means a smaller title or a different location.
Once stability returns and a few months of steady credits are visible, you can look again at tools like a Home Loan Interest Calculator or a limited prepayment so the costlier period during the switch does not stay with you for the full tenure.
Conclusion
Changing employers in the middle of a housing loan plan is manageable if you think like the bank and treat a job change during home loan process as part of your wider financial planning. To an underwriter, a new company or a long probation simply means a fresh look at how stable your EMI really is.
If you feel unsure how your switch, probation clause or salary breakup will land with different lenders, speak to an experienced advisor before you sign the offer letter or the builder agreement, and let ss finadvisory map the timing so your approval and rate stay under control while you focus on the move itself.
Frequently Asked Questions
Q1. Can I change my job after home loan sanction but before disbursement
Ans. You can change, but the bank may pause disbursement till they verify your new employment and see at least one salary credit. Some lenders will also recalculate your eligibility if your income structure has changed. Always inform the bank in advance so the file does not get flagged during final verification.
Q2. Will being on probation affect my home loan approval
Ans. Probation makes banks cautious because it increases the risk of income stopping suddenly. Many lenders still approve if you are with a strong employer and your overall profile is sound, but they might offer a slightly lower loan amount. If possible, time your application a few months into the new job.
Q3. Should I tell the bank if I have only accepted an offer but not joined yet
Ans. Yes, because the bank is judging your future ability to pay, not just your past salary credits. If you hide an accepted offer and HR confirms the change during verification, the credit team can treat it as a red flag. Early disclosure allows them to guide you on timing and required documents.
Q4. Will a higher salary in the new job increase my home loan eligibility immediately
Ans. Not always, especially if the increase is mostly variable pay or incentives. Many banks want to see a track record of variable income before they count it fully for eligibility. A higher fixed component usually supports a higher loan amount faster than a big but untested bonus structure.
Q5. Can I transfer my home loan to another bank while I am on probation
Ans. It is possible, but harder than a transfer from a confirmed role. New banks often want at least six to twelve months of stable income with the current employer before approving a balance transfer. If you are still in probation, it can be smarter to wait till confirmation and then explore offers.
Q6. Does frequent job hopping affect home loan approval in India
Ans. Yes, frequent moves across companies or industries can make underwriters uncomfortable even if your current salary is high. They may reduce the loan amount or offer stricter terms to offset the perceived risk. A more stable job record usually leads to smoother approval and better room for negotiation.