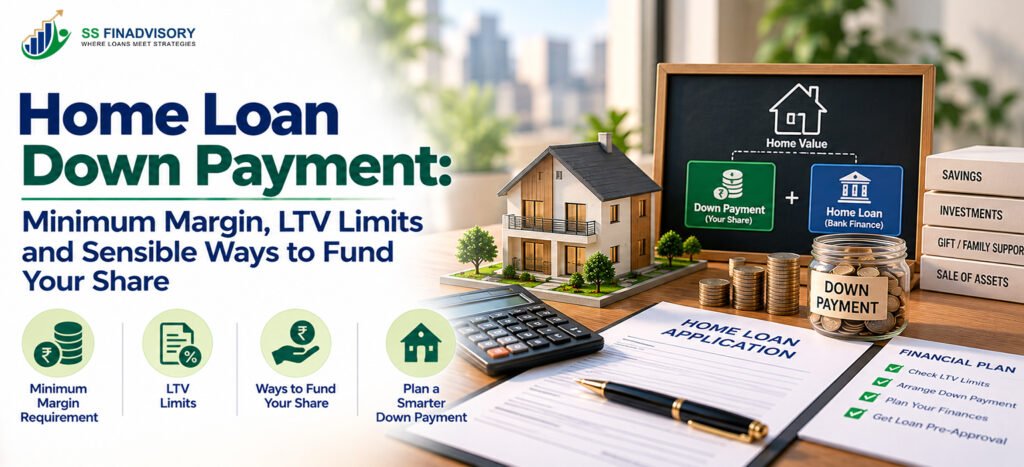
Home loan down payment planning shapes how hard or light your home loan feels against your income for the next couple of decades. Most buyers chase offers and EMI calculators, but the amount you put in, where it comes from and when you pay it quietly decides whether the purchase feels safe or suffocating.
If you understand how banks read property value, margin and loan to value (LTV), you can pick a property budget and contribution with a cooler head. We will walk through how lenders actually calculate the loan, what really counts as your money, safer ways to fund your share and how to line it up with later steps like interest planning and reviews. For resale buyers, guides such as Home Loan for a Resale Flat can sit alongside this one when you compare options.
How Banks Really Look At Value, Margin And LTV
Banks do not lend on the seller’s wish price. They calculate on the lower of the agreement value and their own technical valuation. LTV is simply the percentage of this accepted value that the bank is ready to fund, and your margin is the rest.
Your true margin also absorbs stamp duty, registration and GST on under construction units because banks rarely include these in property value. Once you see that full gap clearly, you can decide how much of your savings you are ready to lock and how much buffer to keep. Our broader home loan down payment guide explains how these choices sit with rate and tenure decisions rather than floating on their own.
Standard Margin Expectations For Different Properties
Margin expectations shift quietly between ready flats, resale homes and under construction projects, and many buyers discover this only when the sanction letter is smaller than they hoped. A new flat from a known developer may see a higher LTV, while an older resale building can face a tighter internal cap and a conservative valuation. If you’d rather hand this part over, it’s the kind of work our Home Loan sanction letter team handles every week.
Older buildings, leasehold properties or those with documentation gaps often see extra cuts from the valuer, so your effective margin jumps even if the advertised LTV slab looks generous. If you are comparing a builder unit with a secondary sale, it helps to read a focused guide like Home Loan for a Resale Flat so you are not surprised later by extra documents, valuation gaps or lower eligible loan amounts.
What Really Counts As Your Own Contribution
Lenders want to see that your share comes from clean, traceable sources, not cash stitched together a day before token payment. Savings in bank accounts, fixed deposits, sale of another asset, EPF withdrawal where rules permit and documented family gifts usually pass without drama.
Where many buyers slip is by taking a personal loan for margin and assuming it is harmless because the tenure is short. In reality, fresh unsecured loans drag down your home loan eligibility check result because the EMI adds to your fixed obligations. Before you block a high ticket property, run a simple income to EMI calculation or talk to someone who can help you Improve Home Loan Eligibility rather than patch the gap with costly credit.
Using Local Advice To Set Budget And Margin Safely
Many buyers call a home loan advisor Kolkata only after paying a token or signing a booking form, which is exactly when it is hardest to change budget or project. A better sequence is to discuss income, existing EMIs, savings and city level prices before you book, so you work with a realistic loan figure, margin requirement and EMI together.
If you are in or around Kolkata, working with a seasoned home loan consultant in kolkata who knows local builders, resale pockets and bank panels can save you from late shocks like low LTV on older buildings or issues around an occupancy certificate. For edge case projects, you may want case specific guidance from posts such as Home Loan Without Occupancy Certificate so you know what to check before you put down a serious advance.
How A Loan Advisor In Kolkata Actually Helps
A good advisor looks beyond the sanction letter and cares about your long term interest cost and risk. Instead of chasing the highest LTV, they sit with you on how much margin you can safely put from current savings and how to keep some cash for future options such as working with a home loan balance transfer consultant if rates change badly.
Someone who works as a true loan advisor in Kolkata will also help you read builder demand letters, understand slab wise schedules and map them to your funds. That support keeps you away from last minute personal loans that feel small at first but later squeeze both eligibility and cash flow. If you are already paying a steep rate, related pieces like Reduce Home Loan EMI Without Extending Your Loan Tenure can help you plan the next move.
Better Ways To Fund Or Trim Your Margin
There are a few clean ways to fund your share without regret, and most start with an honest budget. If numbers are tight, trimming flat size or picking a slightly different location is usually safer than stacking personal loans or informal borrowings on top of a stretched home loan.
Before you commit, sit with numbers for different loan amounts, rates and tenures using a clear Home Loan Interest Calculator. A small cut in property price can bring your EMI back within a safe part of income and avoid a tight structure where every rate move or emergency pushes you toward selling the house. If you already own property, comparisons such as Compare Loan Against Property Offers can show whether a secured top up there makes more sense than short personal loans.
Family Help, EPF And Selling Older Assets
Family support as a documented gift or an interest free loan is common in Indian home purchases, and banks usually accept it when the money trail is clear on paper. An EPF withdrawal for a first home, where rules allow, can cover part of the margin, but you should weigh that against a thinner retirement fund later. It’s one of the first things we look at in any negotiate Home Loan Interest Rate project.
Selling non core assets like a second plot or old investments can also make sense when it lets you keep the new EMI at a safe share of income. Just avoid distress sales at throwaway prices and match the timing of receipts with your builder or seller payment schedule so you are not forced into short term borrowing while the sale is still pending. For resale flats in particular, pairing that sale schedule with the points in Home Loan for a Resale Flat keeps surprises down.
How Margin, LTV And Interest Rate Play Out Over Time
Higher LTV often means more risk for the bank and sometimes a small premium on the rate offered to you. Over 15 or 20 years, even a small rate difference can mean many extra EMIs, so margin, rate and review plans need to be thought through together.
If your profile allows, consider a structure with moderate LTV and a clear plan to review your rate every few years, either through Home Loan Interest Rate Negotiation with your bank or a shift when it makes sense. In some cases borrowers study Home Loan Balance Transfer vs Prepayment to see which path cuts more interest once a few years of EMIs are already paid, then use those savings to reduce home loan interest rate faster through partial prepayments.
Putting Your Home Loan Down Payment Plan On Paper
The most useful step is to write a short plan that covers property budget, expected loan amount, margin, source wise break up and timing of each payment. Add every item so stamp duty, registration, GST and brokerage do not surprise you later, and cross check these figures with your latest home loan eligibility check so the numbers match what banks are likely to offer. We run into this a lot when clients come to us for Loan Against Property Balance Transfer.
Once these numbers are in front of you, match them against your savings plan and family obligations for the next year. If your timeline is flexible, you may prefer to wait, build some more savings and then speak to a home loan agent in kolkata or your bank from a position where your margin is strong and your EMI sits comfortably within income. For bigger loans, posts on how to Home Loan Balance Transfer Mistakes That Could Cost You ₹2 can also be useful because they show what to avoid later when you consider switching.
Conclusion
A clear, written home loan down payment plan for margin, LTV and EMI matters more over twenty years than squeezing out a tiny rate cut on day one. When your share is funded cleanly from sources you are comfortable with and timed to the builder or seller schedule, the process from sanction to registration usually runs with fewer shocks.
If you feel stuck between flat choices, loan offers and family expectations, talk to a steady advisor or a firm like ss finadvisory before you swipe for margin or sign heavy forms. A couple of grounded conversations now can give you a home loan structure that you can live with for a long time without losing sleep, and posts on Home Loan Advisory in Kolkata or Home Loan Balance Transfer vs Prepayment can be good next reads.
Frequently Asked Questions
Q1. How much down payment is usually needed for a home loan in India
Ans. Most banks expect at least 10 to 25 percent of the property value as your own contribution, with lower margins more common on standard apartments. On top of this, you should plan for stamp duty, registration and other charges, which are rarely funded. The exact margin depends on your profile, property type and lender policy.
Q2. Can I take a personal loan to fund my home loan down payment
Ans. Banks usually discourage using fresh personal loans for margin because the EMI reduces your eligibility for the main home loan. It can also raise your overall interest cost sharply because personal loan rates are higher and tenures are shorter. If you need extra funds, it is usually safer to adjust property budget or timeline instead of adding more debt.
Q3. Will a higher down payment reduce my home loan interest rate
Ans. A higher contribution sometimes helps you qualify for a slightly sharper rate or better terms because the lender’s risk drops. The bigger impact is on your total interest over the years because a smaller loan amount cuts interest by itself. It also gives you more comfort during rate hikes because your EMI burden is lower.
Q4. What documents prove my home loan margin money
Ans. Lenders usually ask for bank statements showing transfers to the seller or builder, fixed deposit break up receipts, EPF withdrawal proofs or gift deeds and donor bank statements where family support is used. These documents create a clear money trail from your sources to the property payment. Keeping everything transparent makes sanction and disbursal smoother.
Q5. Is stamp duty and registration cost included in the home loan amount
Ans. Most banks in India do not include stamp duty and registration charges in the property value for LTV calculations, so they are not covered by the main home loan. You should budget and plan to fund these amounts from your own sources. Treat them as part of your overall margin, not as small extras to think about later.
Q6. How early should I plan for my home loan margin
Ans. It is sensible to start planning and saving for your share at least several months before you expect to buy. Early planning lets you build a buffer, arrange any family support and avoid rushed personal loans or forced sale of assets. It also gives you a clearer sense of your true property budget before you start shortlisting flats.