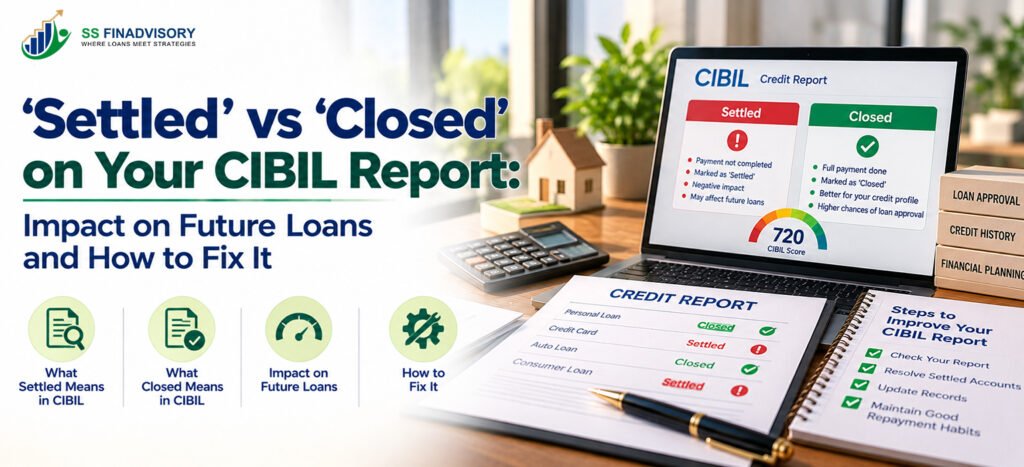
The topic settled vs closed CIBIL sounds technical, but it quietly tells banks how risky you look before every loan approval. If a lender has marked an old loan as settled instead of closed, your report is signalling that you did not repay as agreed and that tag can sit there for years.
Right now you probably care because a home loan, top up or business facility is stuck and your score or remarks are getting in the way. We will walk through what each status really means, how lenders in India read it, what you can realistically fix and where a proper review of your CIBIL Score and Credit Health can change the conversation.
Settled Vs Closed CIBIL: How Banks Read Each Tag
The quickest way to get stuck is to assume settled is almost as good as closed. When an account is marked closed, the bank has received the full amount it was supposed to receive under the contract and there is no loss booked on its books, so the chapter is finished cleanly.
When an account is marked settled, the bank has accepted less than the contractual due and forgiven the rest. Internally that write off sits in their systems as a loss, and future lenders treat that as a strong negative when they look at your previous credit score improvement guidance efforts and overall track record.
How A Settled Status Hurts New Home And Business Credit
Banks in India do not just see a three digit score, they see years of behaviour. Underwriters and scoring models read a settled remark as proof that you either could not or did not repay the full dues, so the file is tagged as higher risk even if recent payments look clean, and that matters to your debt consolidation advice plans too.
In practice, a settled tag often leads to tighter conditions on new borrowing, like lower sanction amounts or extra security such as property or guarantors. Business owners who already worry about their CIBIL MSME Rank (CMR) can find that one settlement on a working capital or term loan makes fresh limits harder to negotiate.
Impact On Home Loans And Property Backed Credit
For many families, home loans and loans against property are the main concern. A recent settlement on a personal loan or credit card often pushes banks to say no to a housing loan unless your income is very stable and the property is strong, so approval becomes far more selective and you may need targeted emi burden reduction plan work before applying.
Some lenders will still discuss options if you have clear collateral and steady income, but they may steer you first towards a specialist route such as Home Loan Low CIBIL rather than giving a standard home loan at the best rate from day one.
Impact On Business Borrowers
For proprietors and small company owners, a settlement on personal or business facilities can be a double hit. Banks often look at both consumer and business reports together when they price limits or set covenants, and that combined picture decides how much flexibility you really have around loan restructuring consultant options.
If past business loans were settled, a new working capital line or business loan consolidation facility may only come with stricter terms or stronger security, even if day to day operations feel stable at your end.
Why The Label Settled Or Closed Shapes Pricing
From your side, the difference between settled and closed can sound like technical language, especially if a call centre agent pushed a one time settlement as a quick way to clear the account. From the lender’s side, that single word separates borrowers who finished the contract as promised from those who did not, and they price you based on that history and their internal view of debt management advisor india style risk.
When a report shows cleanly closed accounts with on time EMI history, lenders are far more relaxed about top ups, longer tenures or bigger tickets. When they see settlements, they may insist that you work through a local specialist such as a loan advisor in Kolkata who can package the case, or the system may just give a flat decline with no chance to explain.
How Long A Settlement Sits On Your Report
A settled status can remain visible on your credit report for years even after the balance is shown as zero. There is no simple six month reset, so you have to treat any serious remark as a long term repair project and plan around it with clear debt consolidation advice instead of guesswork.
The more recent the settlement, the heavier its weight in the lender’s internal scoring. Older settlements, combined with fresh clean history and proper closures, can sometimes be explained during manual review, especially when you are trying to refinance smartly or Reduce Home Loan EMI without fresh damage.
Common Traps That Turn A Clean Account Into A Settlement
Most people do not plan to settle. They slide into it because no one mapped cash flow properly at the start, or because unsecured debt quietly piled up in the background and the repayments no longer fit the income that was coming in, so a proper emi burden reduction plan never got built. If you’d rather hand this part over, it’s the kind of work our increase Home Loan EMI team handles every week.
By the time the bank offers that discount, damage to the report is already visible through late marks and overdues. Many borrowers could have avoided this with early debt consolidation advice or by speaking to a loan restructuring consultant before accounts reached the critical stage and collection teams took over.
Why Discounted Closure Calls Are So Risky
Collection staff often pitch settlements as discounted closure or a special offer that will clean your report. The part they skip is that the discount is coded as a loss on the bank’s side and that is exactly what future lenders see when they read your file, so your report looks weaker for years than it needed to.
If you still have room to refinance and the numbers support it, a more structured solution such as a Loan Against Property for Debt Consolidation can be safer, as long as income is stable and the overall EMI fits your budget.
Repairing A Settled Status Over Time
Once a loan is marked settled, there is no quick button that flips it to closed. A real repair plan has two parts, your behaviour on current accounts and the technical clean up through disputes, letters and negotiations with lenders based on honest credit score improvement guidance. It’s one of the first things we look at in any Loan Against Property EMI calculator project.
On the behaviour side, the priority is simple. Keep every live account clean. No fresh late payments, no new overdues and no bounced EMIs on key loans. Lenders are far more open to someone with one old problem and several years of clean activity than to someone who keeps slipping while asking for debt consolidation advice.
Can A Settled Account Ever Become Closed
Banks sometimes agree to change the status from settled to closed if you later pay the waived amount in full. There is no guarantee and they are not bound to do it, so it depends on the lender, the product and how you approach them in writing, preferably after speaking to a seasoned loan restructuring consultant. We run into this a lot when clients come to us for Loan Against Property Low CIBIL.
If you can see a realistic path to repay the waived component over a few months and the amount is meaningful for your future plans, put a written proposal to the bank. A good debt management advisor india can help you judge whether that extra payment makes sense in your case and how to present it.
Using Consolidation Without New Damage
Consolidation is useful when used early and based on real cash flow, not as last minute fire fighting. Moving expensive unsecured balances into a single structured facility can work if income is stable and the security is strong enough to support the risk that comes with a bigger single EMI.
Borrowers who own property and have mixed exposure often benefit from speaking to a specialist in Home Loan Strategy & Optimisation so that the new structure actually reduces risk instead of just shifting it into one larger loan.
Planning New Loans After Past Settlements
After a settlement, planning new borrowing needs patience and a written plan. Rushing into fresh applications with the old report unchanged usually triggers more hard enquiries and more rejections, which only drag the score down further and push good credit score improvement guidance work backwards.
Start by getting full reports from all major bureaus and reading every line of status, DPD and remarks. Then list which loans are closed, which are ongoing and which were settled or written off, and match that against your income to build a practical emi burden reduction plan instead of random guesses.
Stability First, Applications Later
Lenders care more about recent stability than about a single old mistake, so you need a clean recent track. Give yourself at least 12 to 18 months of on time EMIs on all live accounts before you chase large fresh limits like a big home loan or top up or discuss complex debt consolidation advice structures.
Business owners with scattered facilities and one or two settlements should look carefully at structured solutions such as Consolidate Multiple Business Loans and Credit Facilities Into a Smarter Funding Structure instead of stacking more short term credit on top.
When To Work With An Advisor Instead Of Going Solo
Online tips are fine when your report shows one or two late payments and everything else is clean. Once you see settlements, write offs or repeated overdues, it usually pays to sit with someone who reads credit reports every week and is honest about what can be done, ideally during a focused book loan strategy consultation kolkata style session.
A thoughtful debt management advisor india will go beyond the score, they will map your income, business cycles, existing security and future plans to decide which loans should be closed, which can be refinanced and which should be left alone for now, sometimes after looping in a home loan advisor Kolkata for property backed needs.
What A Real Strategy Consultation Looks Like
For complex cases, a good session feels like joint problem solving. There is detailed document review, a tough discussion on priorities and a cash flow based plan that you can actually follow without new stress every month.
If property or housing is in the picture, many borrowers prefer to work with a Home Loan Advisory in Kolkata service or a loan against property consultant Kolkata who understands local lender appetite and can tie your plan to real offers rather than just theory.
Conclusion
The settled vs closed CIBIL label looks like a single word on your report, but it shapes how every future lender reads your story. Repair is possible if you accept that it needs clean behaviour on current loans, sensible restructuring and, in some cases, fresh payments to old lenders instead of quick fixes.
If you are serious about getting back to healthy borrowing and want a clear plan before you apply again, speak to a qualified advisor in your city or reach out to ss finadvisory for a structured review of your CIBIL Score and Credit Health and your settled vs closed CIBIL history.
Frequently Asked Questions
Q1. Is a settled loan really bad for my CIBIL score in India
Ans. Yes, a settled status is taken negatively by most lenders because it means the bank wrote off part of your dues. It usually hurts more than a few late payments that are later cleared. Over time, strong repayment behaviour on other accounts can reduce the impact, but the remark itself may stay visible for years.
Q2. How soon after a settlement can I apply for a home loan
Ans. There is no fixed rule, but applying immediately after a settlement is risky and often leads to rejection or poor terms. Many borrowers wait at least 12 to 18 months while building a clean payment track on other accounts. During this period, focus on closing small unsecured loans and credit cards properly and keeping utilisation under control.
Q3. Can I ask the bank to change my status from settled to closed
Ans. You can always ask, but banks generally agree only if you pay the remaining waived amount in full and they decide to reconsider. Even then, they are not obligated to change the status. If they do agree, take every confirmation in writing and keep proof of payments safely for future disputes.
Q4. Will paying a settlement amount improve my CIBIL score immediately
Ans. Paying the settlement amount may stop further collection calls and legal escalation, but it does not automatically improve your score. In the short term, the combination of past delays and the settled tag usually keeps your score lower than you expect. Gradual improvement comes from building fresh clean history, reducing unsecured exposure and avoiding new overdues.
Q5. Is it better to take a new loan to close old ones than to settle
Ans. In many cases, refinancing expensive or scattered loans into a better structured facility is safer than settling, but it depends on your income stability and available security. A new loan that stretches your budget can backfire and create fresh stress. Evaluate total cost, tenure and risk carefully and, if needed, discuss options with a professional advisor before you commit.
Q6. Do all banks treat a settled status in the same way
Ans. Different lenders have different risk appetites and policies, but almost all see settled and written off accounts as red flags. Some may still approve with stronger security, higher pricing or lower limits, others may decline outright for a few years after the event. That is why it is important to check your report first and plan applications instead of applying randomly.