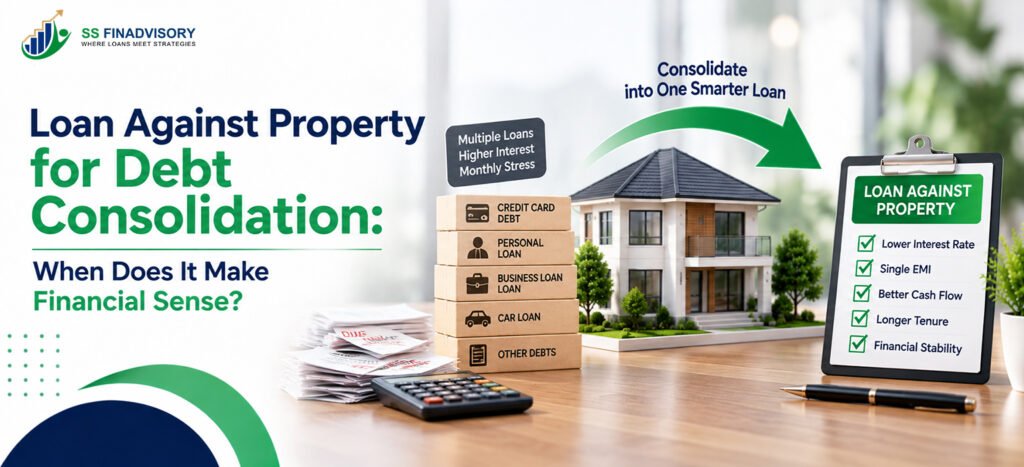
When you start missing EMIs, a loan against property for debt consolidation can feel like the clean reset button you desperately need. But pledging your home or commercial property is a big call, and in India the wrong LAP structure can quietly cost more than the messy loans you were trying to fix.
This guide walks through when using your property to close high-interest loans actually makes financial sense, and when you should step back, renegotiate, or consider a different strategy.
What Exactly Are You Trying To Fix?
Before you even look at a loan against property, write down the real problem you want to solve. Is it too many EMIs on different dates, very high interest rates, or a genuine cash flow crunch where your income can’t support the dues at all?
If the main issue is only that EMIs fall on awkward dates, a simple rescheduling with your lenders might be enough. If you’re paying double-digit interest on multiple unsecured loans or revolving credit card balances, shifting them into one property-backed loan can cut the rate meaningfully, but only if you also fix your repayment discipline.
How A LAP For Debt Consolidation Typically Works
Most people hear about LAP for debt consolidation from a relationship manager who promises a single lower EMI and “huge savings”. In practice, the bank or NBFC gives you a mortgage-style term loan against your residential or commercial property, and you use the proceeds to close existing loans.
The process looks roughly like this: assess property value, check your income and repayment capacity, get a sanction, complete property legal checks, and then disbursement happens directly to your old lenders or to your account for you to repay them. Advisory services like the LAP smart leverage advisory offering on this site focus on getting that structure right instead of just maximising the loan amount.
Key Features Of A Property Backed Loan
Compared to personal loans or credit card rollovers, a property backed loan usually offers a longer tenure and a lower interest rate. In exchange, the lender takes a mortgage over your property, and you accept that default risks losing that asset.
Tenure and flexibility vary a lot across lenders. Some allow part-prepayments without heavy charges, while others lock you in. The more rigid the structure, the more carefully you need to check whether the consolidation actually helps you get debt-free faster.
When Does A Debt Consolidation LAP Make Financial Sense In India?
You should only think of a debt consolidation loan against property if three conditions line up: you genuinely reduce your blended interest cost, you have a realistic plan to close the new loan faster than the old ones, and you’re comfortable offering property as security.
For many salaried and self-employed borrowers in India, the best use case is closing multiple unsecured loans and card balances that carry very high interest. If the new EMI fits comfortably within your monthly cash flow and you commit to not taking fresh short-term loans, consolidation can be the reset that actually sticks.
Reading LAP Interest Rate Offers Correctly
Headline pricing on a LAP interest rate can be misleading. A seemingly small discount versus your current loans may not justify long documentation, processing fees, valuation charges and the risk of mortgaging your property.
What really matters is the effective rate after all charges and how that compares to your current blended cost. In some cases, a home loan top-up or a balance transfer with top-up can be cheaper and simpler than a full LAP; that’s where a structured view like the one used in the services on this site becomes important.
Red Flags: When LAP For Consolidation Is A Bad Idea
Some situations look like consolidation candidates but are better handled differently. Using LAP for debt consolidation is usually a bad idea if your income is unstable, your business model is still untested, or you’re already rolling EMIs using credit cards or fresh loans every month.
In those cases, you’re not solving a rate problem, you’re trying to plug a structural deficit in income. Turning unsecured debt into secured debt can make the eventual fallout much harsher, because the lender now has a clear path to your property if things go wrong.
Common Structuring Mistakes People Make
One of the biggest mistakes is stretching the new LAP tenure just to get the EMI down to a number that “feels” comfortable. That lower EMI often comes at the cost of paying a lot more total interest over the life of the loan against property.
Another frequent error is borrowing more than you need “for safety” and then using the surplus for fresh spending instead of actually closing old loans. If you need help avoiding those traps, the detailed guidance in expert loan against property tips from banking experience can be a useful next read.
How To Decide If Consolidation Will Actually Save You Money
To see if you really consolidate high interest debt and save, start with a simple comparison. List every existing loan: outstanding principal, interest rate, remaining tenure and whether there are prepayment charges.
Then get a clear LAP proposal with the rate, processing fees, other charges and proposed tenure. Compare total remaining interest on your current loans with the projected interest on the LAP, keeping in mind you might be able to prepay a little extra each year if the EMI gap creates room.
Using Advisory Support To Run The Numbers
Most borrowers only see the immediate EMI difference and skip the long-term cost comparison. An advisory service that understands both home loans and LAP can help you model scenarios: status quo, consolidation through LAP, or a mix like home loan balance transfer plus part-prepayment.
For example, if a big part of your debt is an existing home loan, resources like the home loan balance transfer vs prepayment guide can clarify options before you commit your property to a brand new LAP.
Alternatives To A Loan Against Property For Debt Consolidation
A loan against property for debt consolidation is powerful, but it’s not the only route. Sometimes a focused negotiation on one or two costliest loans gives better risk-adjusted relief than mortgaging your house.
Other options include restructuring existing business facilities, shifting to a better priced lender, or using bonuses, incentives or asset sales to aggressively prepay the highest cost debt, even if you keep a few lower rate EMIs running.
Business Borrowers: Think Structure, Not Just Rate
If you run a small or mid-sized business, it’s tempting to pile all short-term and term loans into one LAP and call it a day. That can create a mismatch between long-tenure property funding and short working capital cycles.
Sometimes a better move is to reorganise your business loan stack properly. The detailed guide on consolidating multiple business loans and credit facilities shows how to do that without leaning only on property-backed funding.
Planning Repayment So You Don’t End Up Back In The Same Place
A consolidation only works if you treat it as a one-time clean-up and then change behaviour. After taking a loan against property, create a written EMI calendar, keep a three-to-six-month EMI buffer in a separate account, and avoid using credit cards as an emergency line unless you can clear them in full next month.
Every twelve months, review your LAP outstanding and see if you can prepay a chunk from bonuses or surplus cash. Borrowers who treat their LAP like a flexible ceiling often end up re-borrowing and never see their total debt drop meaningfully.
When To Take Professional Help
If your debt picture involves multiple home loans, business facilities and credit cards, doing this analysis on your own can be overwhelming. A structured conversation with a specialist who understands both property-backed and working capital funding can save you from expensive trial and error.
That’s where the broader business loan working capital planning and related advisory work on this site fits in, helping you align all your borrowings with actual cash flow and risk appetite instead of taking loans one by one.
Conclusion
Used thoughtfully, a loan against property for debt consolidation can convert scattered, stressful EMIs into a clear plan to become debt-free, especially for salaried and self-employed borrowers in India who are paying very high rates on unsecured credit. Used casually, it can shift risk onto your home without delivering real savings.
Before signing, compare total costs, test your repayment plan, and consider independent guidance from ss finadvisory or a similar expert so you’re confident that mortgaging your property is the right move, not just the fastest one.
Frequently Asked Questions
Q1. Is a loan against property for debt consolidation better than a personal loan?
Ans: For larger amounts, LAP is usually cheaper than an unsecured personal loan because the lender has property security. But the paperwork is heavier, you risk your home or commercial property, and the tenure is longer. For smaller top-ups, a short personal loan can sometimes be safer and simpler.
Q2. How do I know if LAP for debt consolidation will really save me money?
Ans: Add up the total interest you’ll pay on all existing loans if you continue as is, then compare it with projected interest on the LAP including processing fees, legal charges and valuation costs. If the LAP doesn’t give you a clear saving and a realistic tenure, the consolidation is probably not worth the risk.
Q3. Can I use a loan against property to close credit card dues and overdrafts?
Ans: Yes, many borrowers use a loan against property to close expensive revolving debt like cards and overdrafts. The key is to permanently stop rolling those facilities after consolidation. If you keep swiping and redrawing, you’ll quickly end up with both a big LAP and fresh short-term debt.
Q4. What risks should I consider before taking a property backed loan for consolidation?
Ans: The biggest risk in any property backed loan is losing the asset if income drops and EMIs are missed for long. You’re also locking yourself into a longer-term repayment, so job stability, business visibility and family plans like children’s education or relocation in India should be factored in before pledging property.
Q5. How is the LAP interest rate decided for debt consolidation cases?
Ans: Lenders typically price a LAP interest rate based on property type and location, your income stability, loan-to-value ratio and credit profile. Better documented income, a lower requested percentage of property value and a clean repayment track on existing loans usually help you negotiate a sharper rate.
Q6. Can business owners consolidate all their loans into one debt consolidation loan?
Ans: Business owners often can, but it’s not always wise to push every facility into a single debt consolidation loan. Short-term working capital needs may be better served through structured business facilities, while only the truly high-cost or messy loans are shifted into LAP. A mixed structure usually balances cost and flexibility better.