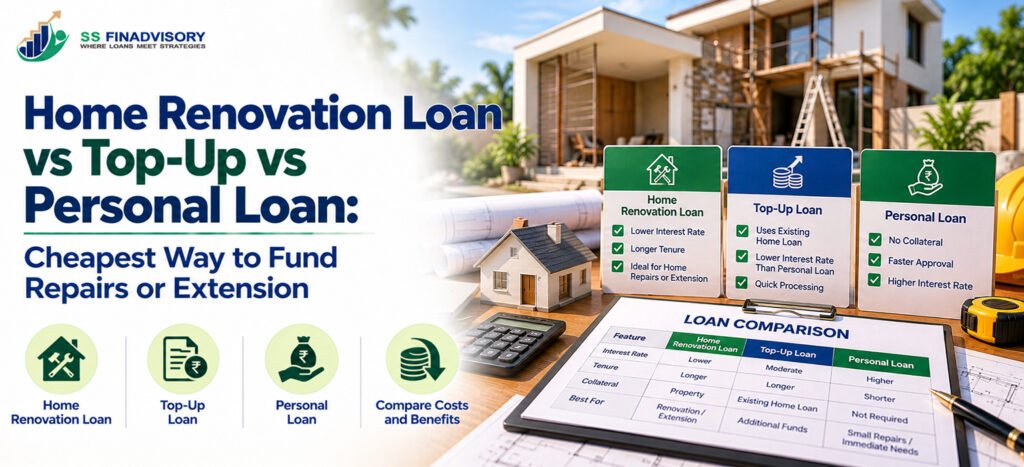
A home renovation loan is simply extra borrowing linked to your house, and the way you fund that work decides how tight your cash flow feels for years after the paint dries. Pick the wrong structure and you could end up paying for tiles and wiring long after they need replacing.
Here we keep the focus on how a home renovation loana top up on your existing home loan or a personal loan actually behaves on cost and risk. You’ll see when each one makes sense, where people quietly give away money in interest, and what to check before you say yes to any lender offer.
Home Renovation, Top Up And Personal Loan: What You’re Really Choosing
Most borrowers hear three names and get confused at once, a home renovation loana top up on an existing home loan and a personal loan. On paper each of these puts money in your account for the contractor, but behind that, the documentation, pricing and impact on your main housing loan are very different.
If you already have a mortgage, the bank will usually push a top up because it rides on the same property and is easy for them to run. Where you don’t have a housing loan yet, or your flat paperwork is messy, lenders often fall back on unsecured personal loans with higher rates and shorter tenures, which hurts more if the renovation budget is large than if you were just fixing a leak, especially if you later try to compare Home Loan Balance Transfer vs Prepayment options.
How A Home Renovation Loan Typically Works
In Indian banks, a dedicated renovation or improvement facility is usually a variant of the standard housing loan meant for structural repairs, interiors and extensions. The bank funds part of the estimated cost based on the property value, your income and standard checks very similar to a regular home loan eligibility check.
Where there is already a running home loan, some lenders add the renovation amount as another tranche under the same account, others create a separate loan with a similar rate and tenure. Either way they’ll want renovation estimates, property documents and updated income proofs, the same kind of paperwork you handled when planning your Home Loan Down Paymentso you should factor this time and effort into your plan.
Rates And Tenure For Home Renovation Loans
Rates on renovation facilities usually sit close to regular home loan rates, sometimes slightly higher because a few banks keep them as a separate product. Tenure is quite flexible, but lenders dislike a renovation loan that runs far beyond the realistic life of the property or the work itself.
For most homeowners, the main point is simple. Borrowing for renovation against property is usually cheaper than unsecured credit, as long as you accept the extra paperwork, processing fees and the fact that your house stays charged to the bank for longer, so it is worth using a Home Loan Interest Calculator to compare real costs.
When A Renovation Facility Can Beat A Top Up
There are cases where a fresh renovation facility priced on the current card rate works out cheaper than the top up rate your bank offers on an old, higher spread home loan. That often happens when your original loan was sanctioned in a different rate cycle and the bank never passed on newer cuts, a topic we unpack in detail in our guide on Home Loan Rate Reset.
If the bank keeps your top up tied to an outdated high spread but quotes a lower rate on a new renovation loan, you should recalculate the EMI and total interest for both options instead of just signing whichever offer reaches your inbox first.
Top Up Loan On Your Existing Home Loan
A top up is extra borrowing stacked on your current housing loan against the same property. Documentation is usually lighter and pricing typically falls between a standard home loan and an unsecured personal loan, and if you’re shifting the loan, a specialised home loan balance transfer consultant can often help you press for better terms with the new bank.
Top ups are common for renovation and for consolidating costlier loans. The quiet risk is that a long top up tenure can keep you paying for work that has already worn out, simply because you chose the maximum allowed term without checking the interest hit or how it affects any future home loan balance transfer vs prepayment decision.
Top Up Vs Dedicated Renovation Loan
For an existing borrower with clean repayment history, banks often quote similar rates for a top up and a renovation loan, then nudge you toward the top up because it moves faster inside their system. In reality the cost gap comes more from tenure, processing charges and how quickly you intend to prepay than from the headline rate alone.
If your renovation budget is modest and you can clear the extra borrowing in a few years, a flexible top up plus later Home Loan Interest Rate Negotiation or part prepayments can work out cheaper than maintaining a separate renovation account for a long period.
Personal Loan For Home Renovation
A personal loan is unsecured credit based on your income profile and credit score with no charge on the property. Approval is fast and documentation is light, which is why many borrowers use it for small or urgent repair work instead of talking to a home loan agent in kolkata or to their relationship manager.
The price of that speed is a higher rate and usually a shorter tenure. Even strong salaried profiles often see personal loan rates well above housing products, and prepayment rules can be tighter than what you’re used to on a home loan, so pairing a small personal facility with a well planned reduce home loan interest rate strategy for the main mortgage can keep overall cost tolerable.
When A Personal Loan Still Works
There are situations where an unsecured loan is the cleaner tool. If the amount is small, the work is urgent and your existing lender is slow to respond, paying more interest for one or two years can be acceptable and far less stressful than delaying critical repair work.
Personal credit can also help in messy property cases where documents are incomplete or the building has compliance issues, something we see often with older constructions and situations similar to those covered in our article on Home Loan Without Occupancy Certificate where banks hesitate to extend any further property backed finance.
Practical Checks Before You Pick A Loan
Your first check is simple but often skipped. Work out the real cost of each option for the amount and tenure you’re considering, including interest and fees on the same assumptions, and use tools like a Home Loan Interest Calculator or a quick call with a home loan advisor Kolkata so you’re comparing total outgo instead of just staring at EMI size.
Next, think about flexibility. If you expect surplus income in the near term, you may value lower prepayment charges more than a slightly cheaper rate, especially if you’re also planning a fresh home loan eligibility check for a new purchase or extension in the next few years.
Costs, Fine Print And EMI Fit
Check your present interest rate, spread and recent reset history before saying yes to any top up or renovation facility. You can refer to your latest statement and to our detailed piece on Home Loan Rate Reset to see whether your pricing is still competitive or has drifted up over time. If you’d rather hand this part over, it’s the kind of work our negotiate Home Loan Interest Rate team handles every week.
Then look at the fine print carefully. Ask for written details of processing fees, legal and valuation charges and prepayment rules on each product, and compare that against how stable your income is and how much variation you can live with in your monthly budget, because stretching tenure only to keep EMI tiny can cost far more overall.
When To Involve A Local Advisor
Renovation choices for your own home are emotional as well as financial, and it’s easy to over borrow when a lender is happy to offer a large top up. Talking to a seasoned home loan advisor early in the planning keeps the numbers grounded in what your income and long term goals can handle so you don’t commit to an EMI that quietly blocks other plans, and articles like Top-Up Loan with Home Loan Balance Transfer can give useful background before you sit down with anyone.
Borrowers in large cities with several bank options often find a well connected home loan consultant in kolkata or similar city level expert useful because they see how different lenders behave at disbursal and during servicing, which rarely shows up in product brochures. For bigger projects, pairing advice on renovation funding with a broader review of Home Loan Strategy & Optimisation often uncovers interest savings you would miss in a quick rate comparison.
How Local Advice Shapes Renovation Funding
A local advisor who sits with your statements, property papers and renovation budget can often spot useful structures that a call centre script will never suggest, including combining a top up with a balance transfer when that matches your cash flow better than a single large new facility, or using a smaller personal loan alongside a tighter top up when tenure risk worries you. It’s one of the first things we look at in any Loan against property Balance Transfer project.
Good advice at this stage can also stop you from mixing short life expenses into long tenure property backed borrowing or from piling expensive personal loans on top of a home loan when one cleaner structure would have handled the full need, and a focused session with a good loan advisor in Kolkata is usually cheaper than a single year of unnecessary extra interest.
Conclusion
Choosing between a top up, a personal loan and a structured home renovation loan is really about matching the credit type to the size and life of your project, without drifting into silent overpayment just because the EMI looks small today. For many owners, a property backed facility with a sensible tenure, sometimes paired with a planned balance transfer or part prepayments, works out calmer and cheaper than quick unsecured credit. We run into this a lot when clients come to us for Home Loan part Prepayment.
If you’re planning significant work on your home and aren’t sure which lender or product mix fits you, a short conversation with ss finadvisory before you sign anything can save money and later stress on your home loan.
Frequently Asked Questions
Q1. Is a top up or renovation loan better for home repairs
Ans. For most borrowers with a running home loan, a top up is simpler and quick for repairs because the bank already knows your profile. A dedicated renovation facility can sometimes be cheaper if it is priced on current interest cards while your existing loan sits on an older, higher spread. You need to compare both on total interest and flexibility, not just EMI.
Q2. Can I use a home improvement loan for furniture and appliances
Ans. Many lenders allow a portion of the sanctioned amount to go toward fixed interiors and built in furniture if it is part of the renovation plan. Loose furniture and standalone appliances are sometimes excluded or capped. It is important to clarify permitted usage with the bank and keep invoices in case they are asked for later.
Q3. Will taking a top up loan affect my home loan balance transfer plans
Ans. A recent top up can affect how other banks view a balance transfer request, especially if your repayment track record is short. Some lenders prefer that the combined outstanding including the top up meets certain seasoning and property value norms. If you are likely to transfer, it is better to plan the timing of the top up and transfer together.
Q4. Is a personal loan ever a good idea for home renovation
Ans. A personal loan can be reasonable for small, urgent repairs where the amount is modest and you intend to close it in a couple of years. The convenience and speed can outweigh the higher rate in such cases. For larger projects or extensions, property backed options usually work out cheaper over time.
Q5. How do banks decide eligibility for renovation finance
Ans. Banks look at your income, existing obligations, credit score and the estimated renovation cost relative to the property value. For existing home loan customers, repayment history matters a lot. They may also check approvals for structural changes, especially if you are extending or altering the building layout.
Q6. Can I prepay a renovation or top up loan without penalty
Ans. For floating rate borrowers, many banks allow part prepayments without penalty, though some set limits on frequency and minimum amounts. Fixed rate top ups or improvement loans often carry some prepayment charge. You should always get current prepayment terms in writing before choosing a product.